🔍

    Category: Income, Tax & Work

    • Foreign Investment Fund (FIF) Tax NZ: The New $100,000 Threshold Explained

      Foreign Investment Fund (FIF) Tax NZ: The New $100,000 Threshold Explained

      Budget 2026 has proposed doubling the Foreign Investment Fund (FIF) tax threshold from $50,000 to $100,000, meaning everyday Kiwi investors will soon be able to hold twice as many direct overseas shares before facing complex Inland Revenue (IRD) tax calculations.

      What is the FIF Regime and Why Does NZ Tax Unrealised Gains?

      If you have been investing through platforms like Sharesies, Hatch, or Kernel, you have probably heard whispers of the dreaded “FIF tax.” Let’s clear the air: FIF stands for Foreign Investment Fund. It is the IRD’s way of taxing Kiwis who own shares in overseas companies or funds.

      New Zealand does not have a comprehensive capital gains tax, but we do tax income. Historically, the IRD noticed a problem: Kiwis were buying growth stocks in the US (like tech companies that reinvest all their profits and pay zero dividends) to avoid paying any tax. Meanwhile, a Kiwi investing in a local New Zealand business paying a 5% dividend was being taxed on that income every year.

      To level the playing field and stop tax revenue from leaking overseas, the government created the FIF rules. Under these rules, if you hold a significant amount of foreign shares, the IRD assumes you are making a return on them—and taxes you on that “deemed” return, regardless of whether you sold the shares or actually received a cash dividend.

      The New $100,000 Threshold: What Changes on 1 April 2026?

      For the last two decades, the FIF rules only kicked in if your overseas investments cost you more than $50,000. This “de minimis threshold” was designed to protect small-time retail investors from accounting nightmares. However, the $50,000 limit was set back in the year 2000 and has never been adjusted for inflation.

      Budget 2026 delivered long-overdue news: a proposal to double this threshold to $100,000.

      • Effective Date: The change is scheduled to take effect from 1 April 2026 (the start of the 2026/2027 tax year).
      • Legislative Warning: It is incredibly important to note that this is a Budget proposal and remains subject to the final legislation passing through Parliament.
      • What it means for you: If your foreign investments remain under this new $100,000 limit, you can ignore the complex FIF rules entirely. You simply declare and pay tax on the actual dividends you receive, exactly as you would with money sitting in a local savings account.

      Cost Basis vs Market Value: The Golden Rule of FIF

      This is where 90% of Kiwi investors get confused. The $100,000 threshold is based entirely on your cost basis, not the current market value of your portfolio.

      Cost basis simply means the actual New Zealand Dollars (NZD) you spent to buy the shares, including the brokerage fees at the time of purchase. The IRD does not care if your tech stocks went to the moon or crashed to zero; they only care about how much money you put in.

      Example 1: The Buy-and-Hold Winner

      Sarah bought $80,000 NZD worth of Vanguard S&P 500 ETFs three years ago. Today, thanks to a massive bull market, her portfolio is worth $130,000.

      Is she caught by FIF? No. Her cost basis is still $80,000. Even though her portfolio value is way over $100,000, she sits safely below the proposed threshold.

      Example 2: The Dividend Reinvestment Trap

      Mark buys $95,000 NZD worth of US shares. He leaves the “auto-reinvest dividends” feature turned on inside his Hatch account. Over the next year, his shares pay out $6,000 in dividends, which are automatically used to buy more shares.

      Is he caught by FIF? Yes. Reinvesting dividends counts as a new purchase. Mark’s cost basis just climbed from $95,000 to $101,000. He has now breached the threshold without ever transferring another dollar from his NZ bank account.

      How Couples Can Effectively Double Their Exemption

      The FIF threshold is a per-person allowance. It is not assessed per household.

      If you and your partner are investing for your future, you can effectively shelter $200,000 of overseas investments from the FIF rules by keeping your finances separated.

      • Partner A can hold up to $100,000 (cost basis) in their own name.
      • Partner B can hold up to $100,000 (cost basis) in their own name.

      If you invest through a joint account, the threshold is typically split, but keeping accounts in individual names makes the accounting much cleaner and ensures neither person accidentally tips the other over the limit. Furthermore, if you are setting up accounts for your children, each child is treated as an individual taxpayer with their own $100,000 threshold.

      Which Platforms and Funds Are Actually Affected?

      Thanks to the rise of easy-to-use digital platforms, Kiwis are sending more money overseas than ever before. But not all investment vehicles trigger the FIF rules.

      New Zealand-domiciled PIE (Portfolio Investment Entity) funds are handled differently. If you buy a global share fund that is structured as a local PIE, the fund manager handles the FIF tax internally. Even better, PIE funds cap your tax rate at 28% (the maximum Prescribed Investor Rate, or PIR), which is a massive benefit if your personal income pushes you into the 30%, 33%, or 39% income tax brackets. PIE funds do not count toward your personal $100,000 FIF threshold.

      Here is a quick reference guide to see what counts toward your limit:

      Platform / Investment TypeCounts Towards Your $100k FIF Threshold?
      Sharesies (Direct US/UK Shares)Yes
      Hatch (Direct US Shares and ETFs)Yes
      Kernel (Direct US Shares)Yes
      Kernel (NZ-Domiciled PIE Funds)No
      Smartshares / Simplicity (PIE Funds)No
      Direct ASX Shares (e.g., Woolworths, BHP)Generally No
      ASX-Listed ETFs (e.g., Vanguard Global ETFs)Yes

      The Australian Exemption Most Kiwis Don’t Know About

      You might have noticed “Direct ASX Shares” listed as exempt in the table above.

      Under IRD rules, shares in most Australian resident companies listed on the Australian Securities Exchange (ASX) are entirely exempt from FIF. The IRD treats these similarly to New Zealand shares. If you buy $150,000 worth of shares in the Commonwealth Bank of Australia or BHP, you don’t need to worry about FIF.

      The Catch: This exemption applies to individual Australian companies. It does not apply to Australian-listed ETFs (Exchange Traded Funds) that invest globally. If you buy an ASX-listed Vanguard global ETF, that absolutely counts toward your $100,000 FIF threshold.

      What Happens if You Cross the Threshold Mid-Year?

      The FIF test is a strict daily measurement.

      If your cost basis breaches $100,000 for even a single day during the New Zealand financial year (which runs from 1 April to 31 March), your entire overseas portfolio becomes subject to the FIF rules for that entire year.

      You cannot simply sell down your shares on March 25th to sneak back under the limit before the tax year ends. Furthermore, the tax applies to every dollar in your portfolio, not just the excess. If your cost basis hits $101,000, you are taxed on the full $101,000—not just the $1,000 that tipped you over the edge.

      If you are hovering near the threshold, you need to turn off automatic dividend reinvestments, closely monitor your foreign currency purchases, and maintain impeccable records of your NZD purchase costs.

      FDR vs CV: How is FIF Tax Actually Calculated?

      If you do cross the threshold, the IRD requires you to calculate your tax using one of two methods. You are allowed to calculate both and choose the one that gives you the lower tax bill, but you must apply the same method to your entire overseas portfolio for that year.

      1. Fair Dividend Rate (FDR) Method

      The FDR method is the most common. The IRD simply assumes your portfolio grew by 5% over the year, based on its opening value on 1 April.

      • The Math: If your portfolio’s market value on 1 April is $120,000, your deemed income is $6,000 (5% of $120,000).
      • The Tax: You then add that $6,000 to your regular income and pay your marginal tax rate on it. If you earn $80,000 from your day job (putting you in the 33% tax bracket), your FIF tax bill will be $1,980.
      • When to use it: FDR is fantastic in a booming bull market. If your portfolio actually grew by 20%, you are only paying tax as if it grew by 5%.

      2. Comparative Value (CV) Method

      The CV method calculates the actual return of your portfolio (capital growth plus any dividends).

      • The Math: (Closing Value + Sales + Dividends) – (Opening Value + Purchases).
      • When to use it: The CV method is your safety net. If the global stock market crashes and your portfolio loses money, your CV return is zero or negative. Because you can choose the lower of the two methods, you would select CV during a market downturn and effectively pay zero FIF tax for that year (though you cannot claim the loss against your day job income).

      Frequently Asked Questions

      Does KiwiSaver count towards my FIF threshold?

      No. Your KiwiSaver is structured as a PIE (Portfolio Investment Entity). Any foreign investments held within your KiwiSaver are managed by your provider, taxed at your Prescribed Investor Rate (up to a maximum of 28%), and do not count toward your personal $100,000 FIF threshold.

      What about my partner’s portfolio?

      The FIF threshold applies per individual taxpayer. Your partner’s investments do not count toward your threshold, provided the investment accounts are in their sole name. If you have joint accounts, the cost base is generally split 50/50.

      Is the $100,000 threshold definitely law yet?

      As of July 2026, the doubling of the threshold from $50,000 to $100,000 was proposed in Budget 2026 and remains subject to legislation passing. It is scheduled to apply retroactively from 1 April 2026, but investors should monitor IRD announcements before relying on it completely.

      What happens if my shares crash in value while under the threshold?

      If your cost basis (what you originally paid) is $90,000, but a market crash drops the value of your portfolio to $60,000, you are still under the threshold. You only pay tax on the actual dividends you receive.

      Can I deduct brokerage fees from my cost basis?

      No, brokerage fees actually increase your cost basis. If you buy $1,000 worth of shares and pay a $5 brokerage fee, the cost basis added toward your threshold is $1,005.

      Conclusion & Next Steps

      The proposed jump to a $100,000 FIF threshold is a massive win for everyday Kiwi investors. It allows for much broader diversification into the US and UK markets without the headache of hiring an accountant just to figure out your fair dividend rate.

      However, the golden rules remain: track your NZD cost basis religiously, beware of automatic dividend reinvestments pushing you over the line, and remember that breaching the limit by a single dollar pulls your entire overseas portfolio into the FIF net.

      If you are getting close to the limit and want to see exactly how much tax you might be on the hook for under both the FDR and CV methods, take the guesswork out of the equation.

      Use our FIF Tax Calculator to see whether you’re likely to be affected and estimate your potential tax bill for the current financial year.

      Disclaimer: This is general information, not personalized financial advice. This article provides general information and educational content only. We are not registered financial advisers. Always speak to a licensed financial advice provider before making major changes to your KiwiSaver fund, investment portfolio, or mortgage strategy.
    • Side Hustle Tax NZ: What to Declare, When & How to Pay Less (Legally)

      Side Hustle Tax NZ: What to Declare, When & How to Pay Less (Legally)

      You’re leaving yourself wide open to a massive tax bill and avoidable penalties if you’re quietly pocketing cash from your side hustle while assuming the IRD isn’t watching. With the cost of living climbing in Aotearoa, and RBNZ LVR restrictions meaning you still generally need a 20% deposit for a home, every extra dollar counts—but you need to make sure the taxman gets his legally required cut before you spend it.

      The Side-Hustle Tax Confusion in NZ (And Why IRD Is Watching)

      New Zealand has a surging side-hustle economy. Whether you’re delivering Uber Eats on the weekends, renting out a sleepout on Airbnb, freelancing as a graphic designer, or flipping vintage clothes on TradeMe, Kiwis are working harder than ever to get ahead and build alternative income streams.

      Yet, most people earning extra income are completely in the dark about their tax obligations. The common myth is that if your side gig is small enough, it simply flies under the radar. But here is the reality for the 2026/2027 tax year: Inland Revenue (IRD) has more data-matching power than ever before. Thanks to modernized systems and new reporting laws, the IRD receives automatic data from domestic banks, property platforms, and gig economy apps. Undeclared income is much harder to hide, and much easier to get caught out on.

      This comprehensive guide is going to break down exactly what you need to declare, how to claim legitimate business expenses so you pay less tax legally, and what the latest platform economy rules mean for your side hustle.

      Is All Side-Hustle Income Taxable?

      The short answer is: mostly, yes. In New Zealand, if you are engaging in an activity with the intention of making a profit, the IRD considers the money you generate from it to be taxable income.

      However, there is an exception for the occasional sale of private domestic assets. If you are just doing a spring clean, clearing out your garage, and selling your old surfboard, a spare fridge, or a pile of your own worn clothes on Facebook Marketplace or TradeMe, that money is entirely tax-free. You are simply recovering a fraction of the personal costs for items you already owned.

      But the moment you start going to op-shops to buy items with the intention of reselling them online for a profit, you cross the line. You are no longer selling private assets; you are trading. That makes your activity a taxable venture.

      Hobby vs. Business: How IRD Distinguishes Them

      This is where a lot of everyday Kiwis get tripped up. You might think selling your homemade candles, baking sourdough for neighbors, or weekend woodworking is just a “hobby,” but the IRD might view it as an unregistered business.

      The IRD doesn’t care what you call your activity. Instead, they look at the inherent nature of what you are doing. Your side hustle is legally considered a business (and therefore taxable) if it meets several of these criteria:

      • Intention to make a profit: You price your goods or services specifically to make money, rather than just asking people to cover the cost of your raw materials.
      • Regularity: You are doing it consistently—such as selling at the Sunday markets every weekend, rather than just having one stall a year.
      • Organization: You keep financial records, have a separate bank account, run a dedicated social media page to attract customers, or have a logo.
      • Time and effort: You invest a significant amount of your time into producing your goods or marketing to find clients.

      If you are just knitting scarves for your flatmates and charging them exactly what the wool cost you, it is a hobby. If you set up an Instagram shop to sell those same scarves at a 50% markup, congratulations—you are now in business and owe tax on your net profits.

      Quick Comparison: Hobby vs. Business

      FeatureHobby (Tax-Free)Business (Taxable)
      PricingCovers cost of materials onlyMarked up to generate a profit
      FrequencyRare, one-off, or highly sporadicRegular, ongoing, structured
      MarketingNone, or word-of-mouth to friendsActive social media, website, paid ads
      Record KeepingNoneTracking sales, keeping receipts, invoicing

      How to Declare Side Income: The IR3 Explained

      If you have a standard 9-to-5 job, your employer takes care of your tax automatically via the PAYE (Pay As You Earn) system. But your side-hustle income isn’t taxed at the source. Because you are essentially operating as a “sole trader,” the responsibility of declaring and paying the tax falls entirely on your shoulders.

      To declare this extra income, you must file an IR3 Individual Tax Return through your myIR online portal at the end of the tax year.

      • The New Zealand tax year runs from April 1 to March 31.
      • If you manage your own taxes, your IR3 return is due by July 7 each year.
      • If you use a registered tax agent or accountant, you usually get an extension until March 31 of the following year.

      Beware the Provisional Tax Trap

      If your side hustle is highly successful and you end up owing the IRD more than $5,000 in end-of-year tax on your IR3, you will automatically be pushed into the Provisional Tax regime for the following year.

      This means instead of paying one lump sum at the end of the year, the IRD will require you to pay your estimated taxes in advance, usually in three instalments (August, January, and May). This catches many side-hustlers off guard, as they suddenly have to pay last year’s tax bill and their first provisional instalment for the current year at the same time.

      How Your Tax is Calculated for 2026/2027

      New Zealand has a progressive tax system. This means you don’t pay one flat rate on everything you earn. Instead, your side hustle income is added on top of your main PAYE salary to determine your final, highest tax bracket (known as your marginal tax rate).

      Here are the confirmed NZ Tax Brackets for the 2026/2027 tax year:

      • $0 – $15,600: 10.5%
      • $15,601 – $53,500: 17.5%
      • $53,501 – $78,100: 30%
      • $78,101 – $180,000: 33%
      • $180,001 and over: 39%

      The Hidden Costs: ACC and Student Loans

      When budgeting for your tax bill, income tax is only part of the equation. You also need to account for the ACC Earner’s Levy. From April 1, 2026, the ACC levy is 1.75% on your taxable income (up to a maximum threshold of $156,641).

      Furthermore, if you have a New Zealand Student Loan, you are required to pay a 12% repayment on every dollar you earn over the annual repayment threshold (which sits at $24,128). Because your primary job likely already pushes you past this threshold, every single dollar of your side hustle profit will trigger a 12% deduction.

      Real NZD Example: Calculating Your Bill

      Let’s look at how the math actually works if you have a full-time job and a side hustle.

      • Your Day Job Salary: $70,000 (Your employer handles PAYE, ACC, and Student Loan on this).
      • Your Side Hustle Net Profit: $10,000 (Money left over after your expenses).
      • Your Total Annual Income: $80,000.

      Because your $70,000 salary already fills up the lower tax brackets, your $10,000 side-hustle money sits entirely at the top.

      1. Income Tax: $8,100 of your profit sits in the 30% bracket (taking you from $70k to $78.1k) which equals $2,430. The remaining $1,900 pushes into the 33% bracket (from $78.1k to $80k) which equals $627. Total Income Tax: $3,057.
      2. ACC Levy (1.75%): 1.75% of your $10,000 profit equals $175.
      3. Student Loan (12%): If you have a loan, 12% of the $10,000 profit equals $1,200.

      Total Bill to IRD: $4,432.

      In this scenario, you need to set aside nearly 45% of your side hustle profits just to stay compliant with the IRD. This is why having a separate bank account and putting a percentage away every time you get paid is absolutely vital.

      Legitimate Deductions You Can Claim

      You only pay tax on your net profit, not your total gross revenue. To legally pay less tax, you need to claim every single legitimate business expense. The golden rule is: if you spent money to make money, you can usually deduct it.

      Common side-hustle deductions include:

      • Equipment and Tools: Laptops, cameras, power tools, or specialized gear. Note: If a single item costs more than $1,000, you cannot deduct the entire cost in the year you bought it. You must capitalize it and claim “depreciation” over its useful life (for example, depreciating a laptop at 50% diminishing value).
      • Software and Subscriptions: Your Adobe Creative Cloud, Xero or Hnry accounting fees, Microsoft 365, web hosting, or domain names.
      • Mobile Phone & Internet: If you use your personal phone for business, you can claim a percentage. If you use it 50% for client calls and 50% for personal scrolling, you can deduct 50% of your monthly bill.
      • Vehicle Mileage: If you use your personal car to drive to clients, pick up supplies, or make deliveries, you can claim vehicle expenses. The easiest method is using the IRD’s mileage rate (which is adjusted annually and sits around $0.95 to $1.04 per kilometre). Crucial rule: You must keep a strict logbook for 90 days recording every trip to establish your business usage percentage. That logbook is then valid for three years.
      • Bank Fees & Interest: Monthly account fees on business accounts, or interest on a loan you took out specifically to fund your side hustle.

      The Home Office Deduction: Getting the Math Right

      If you run your side hustle from your rented house or mortgaged home, you can claim a proportion of your household expenses. This includes rent or mortgage interest (not principal), power, internet, home insurance, and rates.

      You calculate this based on the floor area your workspace takes up compared to the entire house.

      Real NZD Example:

      You rent a 100-square-metre flat in Auckland. You use a 10-square-metre spare bedroom exclusively as your freelance graphic design office. Your workspace is exactly 10% of the house.

      • Total annual rent: $30,000
      • Total annual power: $2,500
      • Total annual internet: $1,000
      • Total household costs: $33,500

      Because your office takes up 10% of the home, you can legally deduct 10% of those costs ($3,350) from your side hustle revenue. This instantly lowers your taxable profit by over three grand, keeping significantly more cash in your pocket at tax time.

      (Note: If you work from the dining room table that is also used for eating, you cannot claim the whole room. You must apportion the claim based on the hours the space is actually used for business versus personal living).

      The GST Threshold: When Do You Need to Register?

      Most casual side hustlers do not need to worry about Goods and Services Tax (GST) when they first start out. You are only legally required to register for GST if your side hustle revenue (your total sales before expenses) exceeds $60,000 in any 12-month period.

      Notice that this is a rolling 12-month period, not a tax year. If you hit $60,000 between October and the following September, you must register immediately.

      If you are earning $20,000 a year doing weekend photography, you do not need to register. You do not add 15% GST to your client invoices, but on the flip side, you cannot claim back the GST on the expensive camera lenses you buy.

      However, if your hustle scales up and you cross that $60k mark, registration is mandatory. Once registered, you must file regular GST returns (usually two-monthly or six-monthly), charge 15% on your goods and services, and you can finally claim back the 15% GST on your business expenses.

      Platform Income: The Rules for Uber, Airbnb, Etsy, and Fiverr

      If your side hustle relies on digital platforms, the rules have tightened dramatically. In April 2024, the NZ Government introduced the “App Tax” for online marketplaces providing short-stay accommodation (Airbnb, Bookabach) or ride-sharing and delivery services (Uber, Uber Eats).

      Here is exactly how this operates for 2026/2027:

      • The 15% Collection: Even if your side hustle makes only $5,000 a year (way under the $60,000 GST threshold), platforms like Airbnb and Uber are legally required to collect 15% GST on the services you provide and pay it directly to the IRD.
      • The 8.5% Flat-Rate Credit: Because you aren’t personally GST-registered and can’t claim back GST on your expenses (like petrol or cleaning supplies), the platform passes an 8.5% “flat-rate credit” back to you to compensate.
      • Your IR3 Obligation: You still need to declare your net income (the money that actually hits your bank account, including the 8.5% credit) on your end-of-year IR3 and pay standard income tax on it.

      For global freelance platforms like Etsy, Upwork, or Fiverr, you are treated as a standard sole trader. Because you are usually paid in USD or another foreign currency, you must convert your earnings into NZD before declaring them. You are allowed to deduct the heavy platform fees and the currency conversion costs as legitimate business expenses on your tax return.

      The $200 Earner Exemption: What It Actually Means

      A common piece of bad advice thrown around Kiwi breakrooms is, “If you earn under a couple hundred bucks, it’s totally tax-free.” This is a dangerous misunderstanding of the IRD’s $200 tolerance rule.

      If your total untaxed income for the entire tax year is under $200, the IRD essentially will not chase you for it. If that $200 is your only undeclared income, you do not have to file an IR3 return.

      Warning: This is a $200 limit per year, not per week or per job. If you mow your neighbour’s lawn once in December for $150 and that is the only side money you make all year across any activity, you’re fine. But if you mow lawns every month and make $1,800 a year, you must declare every single dollar. There is no “$200 tax-free bracket” that you can deduct from your $1,800 total. You owe tax on the whole lot.

      Record Keeping: How to Protect Yourself in 2026

      By law, you must keep all of your business and side-hustle records for seven years. If the IRD decides to audit you, they will want proof of every expense you claimed.

      This includes:

      • Bank statements
      • Invoices you sent to clients
      • Receipts for every business expense
      • Your vehicle logbook
      • Home office square-meterage calculations

      In 2026, you do not need shoeboxes full of fading thermal receipts. Keeping digital copies is perfectly acceptable and preferred by the IRD. Get into the habit of snapping a photo of your receipt on your phone and saving it to a dedicated Google Drive folder. Alternatively, using modern accounting software like Xero, or a purpose-built sole-trader tax service like Hnry, can automate your invoicing, expense tracking, and tax withholding, saving you hours of intense stress come July 7.

      Frequently Asked Questions

      Can I offset side-hustle losses against my PAYE salary?

      Yes, in most general cases. If you operate as a sole trader and your side hustle makes a loss in its first year (for example, you spent $5,000 on tools and marketing but only made $2,000 in sales), that $3,000 loss can usually be offset against your main PAYE salary on your IR3. This effectively lowers your total taxable income, which can result in a welcome tax refund from the IRD.

      Do I need a separate bank account for my side hustle?

      While it isn’t legally mandatory if you are operating as a sole trader, it is highly, highly recommended. Mixing your personal supermarket shopping with your client income is an accounting nightmare. Set up a free, fee-free secondary transaction account with your bank and run all side hustle income and expenses through it. It takes five minutes and is the best thing you can do for your sanity.

      I’m already in the top tax bracket (39%); is a side hustle even worth it?

      If your primary salary is over $180,000, every dollar of profit from your side hustle will be taxed at 39% (plus the 1.75% ACC levy). While handing over 40+ cents on every dollar hurts, you are still taking home nearly 60 cents of pure profit you wouldn’t have had otherwise. It comes down to how much you value your free time—if the hustle is scalable, passive, or something you genuinely enjoy, it is still accelerating your wealth generation.

      Do I get government KiwiSaver contributions on my side hustle?

      Because side-hustle sole trader income is not subject to automatic PAYE KiwiSaver deductions, you aren’t automatically contributing. If you want to claim the government’s maximum annual top-up of $260.72 (as of the 2025/2026 changes), you will need to make sure you voluntarily contribute at least $521.43 to your KiwiSaver provider directly before the end of June each year.

      What if I haven’t declared side hustle income for the last few years?

      Don’t panic, but don’t ignore it hoping it will go away. The IRD looks much more favourably upon taxpayers who make a “voluntary disclosure” than those they catch via an audit. Contact the IRD (or hire a registered accountant to act on your behalf) to declare your past income. You will have to pay the back taxes and likely some interest, but a voluntary disclosure often heavily reduces or completely eliminates shortfall penalty fines.

      Stay Compliant and Keep Growing

      A side hustle is one of the best ways to accelerate your financial goals in New Zealand—whether that is crushing your student loan, aggressively bumping up your KiwiSaver balance, or building a house deposit in a tough market.

      Just remember to treat it like a real business from day one. Track your expenses meticulously, set aside roughly 30% to 40% of your net profits in a high-interest savings account for the inevitable tax bill, and ensure you file your IR3 on time.

      Want to know exactly how much you need to stash away for the taxman? Run your side hustle earnings through our free calculators below to take the guesswork out of your IRD bill.”

      Secondary Tax Calculator | NZ GST Calculator

      Disclaimer: This is general information, not personalized financial advice. Tax laws can be complex and subject to change. Always consult a registered accountant or tax agent regarding your specific financial situation.

    • Provisional Tax New Zealand: A Complete Guide for Self-Employed & Contractors (2026)

      Provisional Tax New Zealand: A Complete Guide for Self-Employed & Contractors (2026)

      You have to pay provisional tax in New Zealand if your untaxed income results in a residual tax bill of more than $5,000 at the end of the financial year, meaning you must pay your income tax in regular instalments rather than a single lump sum.

      When you work a traditional job as a PAYE (Pay As You Earn) employee in New Zealand, tax is virtually invisible. It slides quietly out of your paycheck every fortnight before the cash ever hits your bank account, taking care of your income tax, ACC levies, and KiwiSaver contributions automatically. But the moment you strike out on your own as an independent contractor, freelance designer, or self-employed sole trader, that protective bubble bursts. Suddenly, you are receiving 100% of your gross invoice amounts. While seeing those unclipped sums drop into your business account feels amazing, it comes with a massive catch: a large portion of that cash does not belong to you.

      Many new Kiwi business owners in Auckland, Wellington, and Christchurch get caught out during their second year of trading because they do not prepare for the shift in tax timing that occurs when you are self-employed. Known commonly as the “first-year tax trap,” this phenomenon blindsides thousands of contractors every year, leaving them with unexpected debt and a massive scramble to find money for the Inland Revenue Department (IRD). This comprehensive, up-to-date guide for the 2026/2027 tax year will break down exactly how provisional tax works, help you determine if you need to pay it, compare the calculation methods available to you, and lay out a clear framework to keep your cash flow perfectly protected.

      What Is Provisional Tax and Why Does It Exist?

      The most important thing to understand is that provisional tax is not an additional or separate type of tax. It is simply a method of paying your regular income tax in pre-determined instalments throughout the financial year, rather than waiting to settle the entire bill at the end. The IRD uses this system to keep cash flowing into the government’s coffers steadily, bringing self-employed earners into closer alignment with how PAYE employees pay their tax step-by-step.

      The reason it causes so much stress is the structural lag in New Zealand’s tax calendar. When you first begin contracting or running a sole trader business, you generally do not pay any tax during your first twelve months. You collect your income, pay your business expenses, and wait until the end of the standard financial year (31 March) to file your individual tax return (IR3).

      The financial shock arrives in your second year. Once you file that first tax return, the IRD will issue you a bill for your first year’s earnings, known as terminal tax. However, because they now know your business is consistently profitable, they will also require you to start paying provisional tax instalments for your second year at the exact same time. This creates a “double tax year” effect where you are paying off last year’s tax while simultaneously pre-paying the current year’s tax. If you haven’t budgeted for this accumulation, it can completely cripple a young business’s working capital.

      The $5,000 Residual Income Tax (RIT) Threshold

      Whether or not you have to step onto the provisional tax treadmill depends entirely on a metric called Residual Income Tax (RIT). In plain English, your RIT is your total individual income tax liability for the financial year minus any tax that has already been deducted at source (such as PAYE from a part-time job, schedular payments deducted by a recruiter, or Resident Withholding Tax on your bank interest accounts).

      For the 2026 and 2027 tax years, the entry threshold stands firmly at $5,000 of RIT.

      • If your RIT is $5,000 or less: You are exempt from provisional tax rules. You simply file your annual IR3 return and pay your full tax bill as a single terminal tax lump sum the following year.
      • If your RIT is more than $5,000: You automatically enter the provisional tax system for the next financial year. The IRD will notify you of your obligation and assign you payment dates.

      The Three Provisional Tax Methods Compared

      To offer flexibility for different styles of business, the IRD allows you to choose from three core methods to calculate and pay your interim tax. Selecting the right path can be the difference between smooth financial sailing and severe cash constraints.

      1. The Standard (Uplift) Method

      This is the automatic, default option used by the overwhelming majority of Kiwi sole traders and contractors. It looks backward to find safety. The IRD takes the RIT from your most recently filed tax return and adds a 5% uplift to it, operating on the assumption that your business will grow slightly year-on-year.

      If you have not filed your previous year’s tax return yet when an instalment falls due, the IRD looks back two years and applies a 10% uplift instead. The major advantage of the standard method is its “safe harbour” feature: if your income unexpectedly skyrockets during the year, you are protected from interest penalties as long as you pay your uplifted amounts on time.

      2. The Estimation Method

      If you know with absolute certainty that your business is going to make significantly less money this year than last year — perhaps because you are taking parental leave, downscaling your client list, or dealing with a major market downturn — you can actively choose to estimate your tax.

      You calculate what you expect your current year’s RIT to be, and the IRD divides that number across your payment dates. The massive risk here is precision. If you underestimate your earnings and end up paying less than your actual year-end tax liability dictates, the IRD will charge you backdated interest on the shortfall.

      3. The AIM (Accounting Income Method)

      AIM is a modern, software-driven “pay-as-you-go” system designed specifically for small businesses and contractors with an annual gross turnover under $5 million. Instead of predicting the future or relying on ancient history, AIM connects directly into cloud accounting platforms like Xero or MYOB.

      Your software automatically calculates your exact tax liability at the end of every month or two-month cycle based on your real, actual profits. If you have a terrible month with zero profit, your tax liability for that period is $0. If you have a massive trading month, you pay more. It largely eliminates year-end surprises and interest exposure.

      Feature / MetricStandard (Uplift) MethodEstimation MethodAIM (Accounting Income Method)
      How it is CalculatedPrevious year’s RIT + 5% upliftYour own forecast of current year profitReal-time calculations via software
      Best Suited ForStable, predictable, or growing businessesDeclining businesses or those closing downHighly seasonal or volatile incomes
      Interest Risk (UOMI)Extremely low (protected by Safe Harbour)High risk if you underestimate your incomeNo interest risk if software settings match
      Payment Frequency3 instalments per year (for standard filers)3 instalments per year (for standard filers)Matches your GST filing dates (monthly/2-monthly)

      2026/2027 Provisional Tax Instalment Dates

      For the vast majority of Kiwi self-employed individuals running on the standard 31 March financial balance date, your provisional tax is broken into three equal chunks across the year. If a due date lands on a weekend or a public holiday, the deadline naturally rolls over to the next official working business day.

      The standard layout for the 2026/2027 tax cycle is structured as follows:

      InstalmentDue Date (Standard 31 March Balance)Payment Breakdown
      Instalment 1 (P1)28 August 20261/3 of your total provisional tax liability
      Instalment 2 (P2)15 January 20271/3 of your total provisional tax liability
      Instalment 3 (P3)7 May 2027Final 1/3 of your total provisional tax liability
      Terminal Tax7 February 2028 (or 7 April 2028 if you use a tax agent with an extension of time)The final square-up balance after your actual return is filed

      Important variation: If you are registered for GST and choose to file your GST returns on a 6-monthly basis, your provisional tax instalments drop from three payments down to two. These align with your GST deadlines and fall on 28 October and 7 May each year.

      How to Calculate Under the Standard Method: A Real Example

      Let’s look at how the math actually applies to a real-life Kiwi sole trader using the standard uplift pathway.

      Meet Liam, a freelance construction contractor based in Christchurch. For the financial year ending 31 March 2025, Liam’s total self-employed profit left him with a final Residual Income Tax (RIT) bill of $18,000. Because this comfortably clears the $5,000 threshold, Liam is required to pay provisional tax for the 2025/2026 tax year.

      Here is how his calculations play out step-by-step:

      1. Calculate the 5% uplift: The IRD takes his 2025 RIT and adds the mandatory 5% buffer.
        $18,000 × 1.05 = $18,900 total 2025/2026 provisional tax liability
      2. Divide into the standard dates: Because Liam files GST on a standard 2-monthly basis, his total is split into three equal parts.
        $18,900 ÷ 3 = $6,300 per instalment

      Liam pays $6,300 on 28 August 2025, $6,300 on 15 January 2026, and $6,300 on 7 May 2026.

      When the 2026 financial year concludes, Liam’s business has boomed, and his actual real tax liability for the year finishes at $22,000. Because Liam used the standard uplift method and paid every single instalment on time, he faces no interest penalties for the difference. He simply pays the remaining balance of $3,100 ($22,000 actual tax minus the $18,900 already paid) as terminal tax on 7 February 2027 — or 7 April 2027 if he’s registered with a tax agent who holds an extension of time.

      The Consequences of Underpaying: UOMI & Penalties Explained

      Failing to meet your provisional tax due dates triggers an aggressive response from the IRD’s automated systems. If you miss a deadline, late payment penalties hit you immediately:

      • A 1% penalty is added to the outstanding balance the very day after the payment was due.
      • An additional 4% penalty is applied to the debt seven days later if it remains unpaid.

      In addition to these static penalties, the IRD charges a daily variable interest rate called Use-of-Money Interest (UOMI). The IRD treats any underpaid tax as a line of credit you have taken out from the New Zealand government. These rates are reviewed periodically by IRD, so it’s worth confirming the current figures on IRD’s website before relying on them — as of early/mid-2026 they sit at:

      • The Underpayment (Debit) Rate: The IRD charges 8.97% per annum on any underpaid tax balances, calculated daily from the day after the due date until the principal is cleared.
      • The Overpayment (Credit) Rate: If you overpay your tax, the IRD does pay you interest, but only at a rate of 2.25% per annum.

      The $60,000 Safe Harbour Rule: If your actual RIT for the current year is less than $60,000, and you have calculated and paid all your provisional tax instalments on time using the standard uplift method, you are deemed a “Safe Harbour” taxpayer. This means the IRD will not charge UOMI on any shortfall for your instalment dates during the year. Interest will only start ticking if your final wash-up bill isn’t settled by your terminal tax date the following year. However, if your RIT exceeds $60,000, safe harbour protection dissolves, and UOMI can be backdated to earlier instalments.

      Managing Cash Flow: The 30% Savings Account Rule

      To prevent provisional tax from ever keeping you awake at night, you need to implement a strict, non-negotiable cash flow management routine inside your business banking.

      1. Establish a dedicated tax account (immediate action): Open a completely separate, high-interest business savings account with your bank that is entirely divorced from your everyday business operating account. Label it clearly as ‘Tax Reserves’ so you are never tempted to touch it for general overheads.
      2. Enforce the 30% rule on every single payment (ongoing discipline): Every time a client pays an invoice, immediately calculate 30% of the gross cash that landed in your account and transfer it straight into your dedicated tax account. If an invoice is for $1,000, $300 moves instantly to the tax account before you pay yourself or clear any expenses.
      3. Factor in ACC levies and KiwiSaver additions (monthly balance check): Remember that your 30% savings bracket isn’t just protecting you from income tax. It also needs to cover your annual ACC bill. As a self-employed person you’ll typically pay the ACC Earners’ levy (around 1.75% of your liable earnings for 2026/27) plus a Work levy that varies depending on your industry classification, plus a small Working Safer levy — so your total ACC bill is usually higher than the earners’ levy figure alone. Budgeting a bit extra here, along with room for any personal KiwiSaver lump-sum deposits to capture the government member contribution, will keep this line item from catching you out.

      Tax Pooling: The Legal Safety Net for Kiwi Contractors

      If you hit a cash flow bottleneck — perhaps a major commercial client defaults on their payment terms or goes under, leaving you unable to make an upcoming provisional tax instalment — do not despair, and do not simply leave it to accumulate penalties with the IRD. New Zealand law provides a highly efficient system called tax pooling.

      Authorised intermediaries like Tax Management New Zealand (TMNZ) and Tax Traders operate large, government-regulated pools of tax credits. If you miss an instalment date or discover at the end of the year that you have underpaid significantly, you can buy tax credits from these pools retrospectively.

      Because you are effectively “purchasing” tax that another company paid to the IRD on time back on that specific date, the IRD recognises the payment as met chronologically. This allows you to wipe out late payment penalties and lower your interest costs compared to standard IRD UOMI rates. It provides a vital commercial pressure valve for contractors who experience volatile cash cycles.

      Frequently Asked Questions

      Do I have to pay provisional tax in my very first year of self-employment?

      No, in the vast majority of cases, you do not pay provisional tax during your first year because you do not have a filed historical tax return that shows a residual income tax liability over $5,000. However, do not mistake this for a tax holiday. You are still actively accumulating an income tax liability on every dollar you earn; it simply won’t be collected until your terminal tax date arrives in your second year of trading.

      Can a sole trader use the AIM method?

      Yes, absolutely. Any independent contractor, sole trader, or freelancer can use the Accounting Income Method (AIM) provided their gross annual business income stays below $5 million. To do this, you must use an approved cloud accounting software system (like Xero or MYOB) that is actively set up to submit your real-time financial profiles directly to the IRD.

      What happens if I use the Estimation method and my business revenue drops even further?

      If you choose the estimation method and notice halfway through the year that your income has dropped significantly below your original guess, you can submit a revised, lower estimate to the IRD through your myIR account at any point before an instalment deadline. The IRD will recalibrate your remaining payments downwards, ensuring you don’t over-drain your active operational cash.

      Is Use-of-Money Interest (UOMI) tax-deductible?

      Yes. If you are charged UOMI by the IRD on an underpayment of business income tax, that interest expense is generally tax-deductible against your business income in the financial year it is incurred. Conversely, if you receive UOMI credit interest from the IRD due to overpaying your tax, that interest is considered taxable income and must be declared on your annual return.

      Protect Your Business Cash Flow from the Tax Shock

      Provisional tax shouldn’t be a source of constant dread or a mathematical mystery. By identifying your exact RIT limits early, choosing a payment method that complements your income frequency, and strictly allocating around 30% of every dollar that clients pay you into an untouchable tax account, you can keep the IRD completely satisfied while keeping your sole trader operation highly liquid and safe.

      Are you interested in seeing exactly how your financial take-home position shifts compared to fixed corporate structures? Head over to our Contractor vs Employee Calculator to model your structural tax brackets, analyse your potential write-offs, and map out your optimised path forward.

      Disclaimer: This is general information, not personalized financial advice. This article provides general information and educational content only. We are not registered financial advisers. Always speak to a licensed financial advice provider.

    • ACC Levies Demystified: What Every NZ Worker & Contractor Pays in 2026

      ACC Levies Demystified: What Every NZ Worker & Contractor Pays in 2026

      You’re leaving money on the table if your savings are sitting in a standard transaction account while NZ interest rates are hovering around 5-6%, but even more importantly, you might be losing money to misclassified ACC levies if you haven’t checked your business codes lately.

      If you’ve ever looked closely at your payslip and wondered what the cryptic deduction listed as “ACC,” “ACC Levy,” or sometimes an abbreviation like “ACCEAR” is eating into your hard-earned cash, you aren’t alone. Every working New Zealander pays into the Accident Compensation Corporation (ACC) scheme. But despite it being one of our biggest payroll deductions after income tax and KiwiSaver, most workers don’t know exactly what it funds, how it’s calculated, or what the rules are if they decide to go self-employed.

      Whether you’re a salaried office worker in Wellington or a tradie running your own business in Auckland, this guide will demystify the ACC levy NZ 2026 rates, explain the vital difference between employee and contractor levies, and show you exactly how to take control of your contributions.

      What is ACC and Why Does It Exist?

      New Zealand has a completely unique approach to personal injury. Back in 1974, we gave up the right to sue someone if they accidentally injured us—a system that clogs the courts in places like the United States. In exchange, the government created a comprehensive, “no-fault” personal injury cover system: ACC.

      ACC exists to make sure that if you trip over the dog at home, break your leg playing social netball on the weekend, or suffer a repetitive strain injury at work, your medical costs and lost wages are partially covered. You don’t have to prove someone else was at fault; the scheme covers you regardless of how the accident happened.

      However, this national insurance scheme isn’t free. It is funded directly by the people who live, work, and drive in New Zealand. As a worker, you pay your share through an income levy.

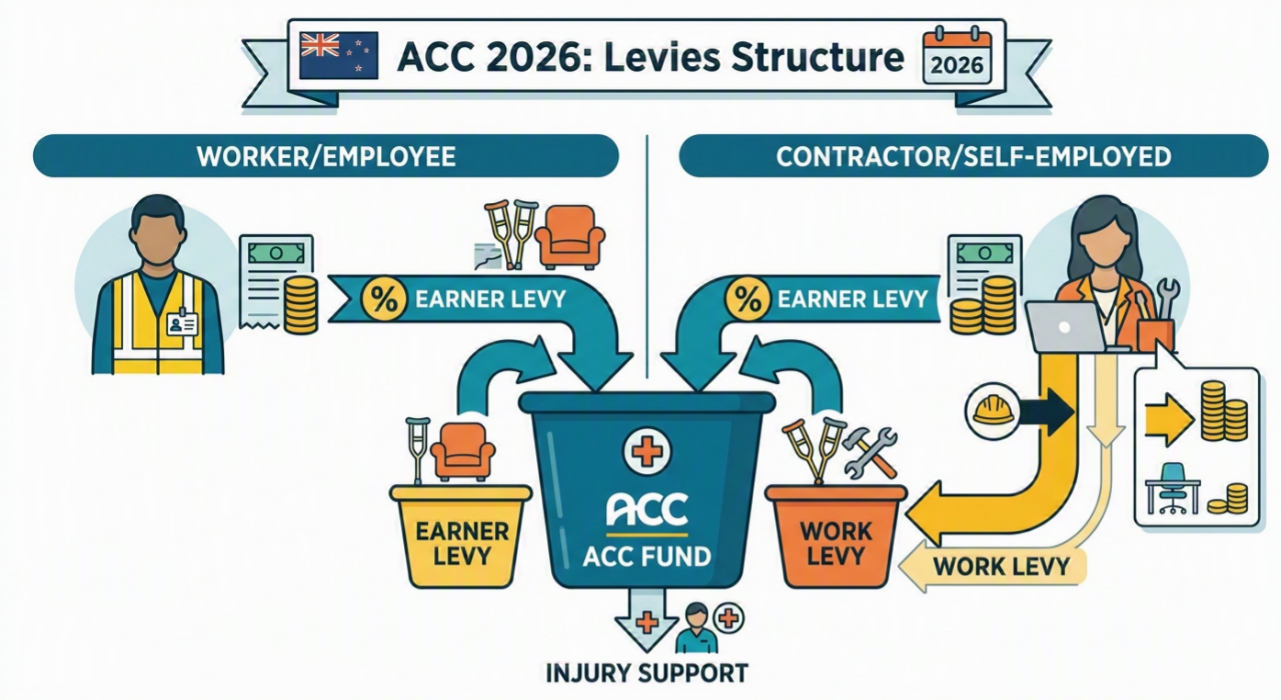
      The Two Main Types of ACC Levy: Earner Levy vs Work Levy

      If you are trying to figure out how much is ACC levy NZ going to cost you, you first need to understand that the scheme is split into different “accounts.” The two that affect your income are the Earner Levy and the Work Levy.

      The Earner Levy

      This is paid by absolutely everyone who earns a wage or salary. It covers you for non-work-related injuries (like coming off your mountain bike on a Saturday or burning yourself while cooking). If you are a standard employee, this is the only ACC levy you pay, and your employer deducts it automatically via the PAYE system.

      The Work Levy

      This is paid by employers and self-employed people. It funds recovery for injuries that happen specifically on the job. The amount paid is heavily dependent on the risk of your industry. A scaffolding company pays a much higher Work Levy than an accounting firm because the statistical risk of a workplace accident is far greater.

      If you are an employee, you only pay the Earner Levy. If you are a self-employed sole trader or contractor, you wear both hats—meaning you pay both the Earner Levy and the Work Levy out of your own pocket.

      If you want to see how this impacts your bottom line, use our Hourly-to-Take-Home-Pay-NZ to estimate your annual costs.

      The 2026 ACC Earner Levy Rate & Annual Cap

      Let’s look at the hard numbers for the 2026/2027 tax year. ACC periodically reviews its rates to ensure the scheme remains sustainable, and a scheduled increase took effect recently.

      Effective from 1 April 2026, the ACC Earner Levy rate is 1.75% (or $1.75 for every $100 you earn). This is a vital update to keep on your radar, especially if you are budgeting for the year ahead.

      However, there is a limit to how much ACC can take from high-income earners. For the 2026 tax year, the maximum liable earnings cap is set at $156,641.

      If your salary is $200,000, you only pay the 1.75% levy on the first $156,641. Anything you earn above that cap is completely exempt from the ACC Earner Levy. This means the absolute maximum Earner Levy any individual will pay in 2026 is $2,741.22 per year.

      2026 ACC Earner Levy by Income (Weekly Deduction)

      To make it easy to see how this impacts your budget or your flatmates’ shared finances, here is a breakdown of the standard weekly ACC deduction based on various annual salaries:

      Annual SalaryAnnual ACC Levy (1.75%)Weekly ACC Deduction
      $40,000$700.00$13.46
      $60,000$1,050.00$20.19
      $80,000$1,400.00$26.92
      $100,000$1,750.00$33.65
      $130,000$2,275.00$43.75
      $156,641 (Cap)$2,741.22$52.72
      $180,000+$2,741.22 (Capped)$52.72

      How ACC Is Deducted From Your Payslip

      If you are a standard PAYE employee, you never actually have to write a check to ACC. Your payroll software calculates it automatically. You might see it listed as “ACC,” “ACC Earner Levy,” or an internal code your payroll provider uses.

      Note on “ACCEAR”: You may have seen this code in older threads or specific legacy payroll software. It is not an official IRD or ACC term. If you don’t see it on your payslip, don’t panic—check for “ACC” or “Levy” instead.

      Let’s look at a realistic example for a mid-level professional earning $75,000 a year in 2026.

      • Gross Annual Salary: $75,000
      • Income Tax (2026 IRD Brackets): -$14,720.50
      • ACC Earner Levy (1.75%): -$1,312.50
      • Net Take-Home Pay: Roughly $58,967 (before other deductions like KiwiSaver).

      In this scenario, our worker is paying about $25 a week toward ACC. It’s a noticeable chunk of change, but it ensures that if they are injured and off work for more than a week, ACC will step in to cover up to 80% of their pre-injury income.

      Self-Employed & Contractors: How to Calculate and Pay the Work Levy

      Things get vastly more complicated when you leave the comfort of standard employment and become a sole trader or contractor. Because you are essentially your own employer, you are responsible for paying ACC directly.

      When you file your IR3 tax return at the end of the financial year, the IRD shares your income data with ACC. A few months later, you will receive an invoice directly from ACC. This invoice will include:

      1. The Earner Levy: 1.75% of your declared profit (up to the $156,641 cap).
      2. The Work Levy: A percentage based entirely on the risk profile of your job.
      3. The Working Safer Levy: A tiny flat rate that goes toward WorkSafe NZ.

      The Minimum Liable Earnings Trap

      Here is a massive trap for new contractors in 2026: If you work full-time (more than 30 hours a week), ACC applies a “minimum liable earnings” threshold. For the 2026/2027 tax year, this minimum is $50,501.

      If your new business struggles in its first year and you only make $30,000 in profit, ACC will still calculate your levies as if you earned $50,501. They do this because if you get injured, they have to pay you a minimum liveable wage. If you work less than 30 hours a week, you must declare yourself as part-time to ACC to avoid being hit with this minimum threshold charge.

      The BIC Code

      Your Work Levy rate is dictated by your Business Industry Classification (BIC) code. A freelance graphic designer sitting at a desk might pay a Work Levy of just $0.15 per $100 of income. A forestry worker operating chainsaw might pay $3.50 per $100. Ensuring your accountant or bookkeeper uses the exact right BIC code is crucial, or you will overpay.

      ACC CoverPlus vs CoverPlus Extra: What’s the Difference for Sole Traders?

      By default, every self-employed person is placed on a policy called CoverPlus.

      Under CoverPlus, if you are injured and can’t work, ACC will pay you up to 80% of the taxable profit you declared in your most recent financial year.

      The problem? Business income fluctuates. If you had a terrible year, took time off, or bought a massive piece of machinery (like a new digger) that artificially drove down your taxable profit, your ACC cover will be dangerously low.

      The alternative is CoverPlus Extra (CPX).

      CPX is an agreed-value policy. You sit down with ACC and mutually agree on a set level of income cover—regardless of what your actual financials show. If you agree on $80,000 of cover, you will pay levies based on $80,000. If you break your leg the following week, ACC pays out based on that $80,000 figure.

      How to Dispute an ACC Levy Invoice

      If you open the mail and are shocked by a massive ACC bill, don’t panic. Errors are incredibly common, particularly for sole traders. The most frequent culprit is the wrong BIC code being assigned to your profile.

      To dispute or fix an invoice:

      1. Do not ignore it; late penalties apply.
      2. Log into your MyACC for Business portal online.
      3. Check the BIC code listed under your profile.
      4. If it doesn’t reflect your daily activities, search for a more accurate, lower-risk code and request a change directly through the portal.
      5. ACC will typically recalculate the invoice and issue a credit note for the difference.

      Frequently Asked Questions

      Is ACC deducted on investment income?

      No. The ACC Earner Levy strictly applies to “personal exertion” income. This means wages, salary, and business contracting profits. Passive investment income—such as interest from term deposits, dividends from shares, or returns from a PIE fund—is entirely exempt from ACC levies.

      Do I pay ACC on rental property income?

      Generally, no. Standard residential rental income (like having tenants in an investment property) is considered passive income and is not liable for ACC. The only exception is if you are running a registered commercial accommodation business, like a multi-unit motel or a highly commercialized short-term rental operation, which requires significant personal exertion.

      Can I opt out of ACC and just use private insurance?

      No. ACC is a compulsory, universal social insurance scheme. You cannot opt out of paying the Earner Levy, even if you hold comprehensive private income protection or health insurance. Private insurance is designed to work alongside ACC (for example, by covering illnesses, which ACC does not cover, or topping up the remaining 20% of your lost income).

      What happens if I have multiple jobs? Do I overpay?

      If you have a primary job and a side hustle, both employers will deduct the ACC levy from your paychecks. If your combined income from all sources exceeds the 2026 cap of $156,641, you will inevitably overpay your Earner Levy during the year. Fortunately, the IRD reconciles your taxes at the end of the financial year, and they will automatically calculate the overpayment and refund the excess ACC directly to your nominated bank account.

      Conclusion

      While nobody loves seeing deductions on their payslip, the ACC scheme provides a world-class safety net that ensures Kiwis aren’t left financially destitute after an accident. For standard employees, the 2026 rate of 1.75% is fixed and handled for you. But if you are stepping into the world of contracting, treating your ACC levies with the same respect as your income tax will save you from nasty cash-flow surprises at the end of the year.

      Disclaimer: This is general information, not personalized financial advice. ACC rates, tax brackets, and rules are subject to legislative changes. For customized tax or levy advice, please speak to a registered accountant or financial adviser.

      Date: 28/06/2026

      Author: Luca Tariciotti

    • NZ Tax Refund Guide 2026: Claim Your IRD Money

      NZ Tax Refund Guide 2026: Claim Your IRD Money

      You could be leaving hundreds of dollars on the table with Inland Revenue (IRD) right now if your employment circumstances changed, you worked multiple jobs, or you donated to charity over the past tax year. With the cost of living in Wellington and across New Zealand climbing, every extra dollar of your own money counts toward your financial goals—whether that’s fighting off inflation or padding your home deposit to meet the latest RBNZ LVR requirements.

      The Mechanics of an IRD Tax Refund: Why Does the Government Owe You?

      New Zealand operates on a Pay As You Earn (PAYE) tax system for wage and salary earners. In theory, this is designed to make tax time entirely frictionless. Every time your employer runs payroll, their accounting software automatically calculates a slice of your gross income, deducts it, and forwards it straight to Inland Revenue on your behalf.

      However, the PAYE calculation engine makes one massive assumption: it assumes that whatever you earn in a single pay cycle (whether that is weekly, fortnightly, or monthly) is exactly what you will earn every single pay cycle for all 52 weeks of the financial year (which runs from 1 April to 31 March).

      If you have a perfectly stable salary, never take unpaid time off, and have no side income, PAYE gets it right down to the cent. But if your financial life is dynamic—if your hours fluctuate, if you change jobs, or if you take time off—the rigid math of PAYE breaks down. Because New Zealand uses a progressive tax system with shifting 2026 brackets (where income over $53,500 is taxed at 30%, and income over $78,100 jumps to 33%), earning heavily in one month and earning nothing in the next will confuse the system. It will tax your high-earning month as if you are a high-income earner year-round, resulting in a systemic overpayment of tax.

      When the financial year ends on 31 March, the IRD tallies up exactly what you actually earned over the 12 months, compares it to the total PAYE you already paid, and refunds you the difference.

      📊 Check Your Rates: Think your employer might be deducting the wrong amount week-to-week? Use our Hourly to Take-Home Pay Calculator to verify your correct PAYE code and see your true net income. If you’re working more than one gig, you can also check our Secondary Tax Calculator to make sure you won’t get hit with a bill at year-end.

      The Top 5 Reasons You Might Be Owed Money in 2026

      Millions of dollars sit unclaimed in Inland Revenue‘s accounts each year. To understand if a chunk of that belongs to you, let’s look at the most common triggers for tax overpayments.

      1. You Worked Multiple Jobs or Changed Employers

      If you moved to a new company mid-year, your final pay from your old job (including paying out your accrued annual leave) might overlap with your first pay from your new job. This overlap artificially inflates your earnings for that specific week, often pushing you into a higher tax bracket momentarily.

      Furthermore, if you worked a second job or a side hustle, you were likely put on a secondary tax code (such as SB, MH, or MS). These codes are notoriously conservative. Because your second employer doesn’t know how much you earn at your primary job, they withhold tax at a flat, often higher rate to prevent you from getting a massive tax bill at year-end. This safety buffer frequently results in you paying more than your actual 12-month average requires, leading to a refund.

      2. You Experienced an Employment Gap

      If you left the workforce for part of the year—perhaps you traveled overseas, took extended parental leave, went back to university, or experienced redundancy—you are highly likely to be owed a refund.

      Remember, PAYE taxes your weekly paycheck assuming you’ll earn that amount 52 times. If you earned $1,500 a week for 20 weeks and then stopped working, you paid tax at a rate designed for someone earning $78,000 a year. In reality, your annual income was only $30,000. Under the 2026 New Zealand tax brackets, the first $15,600 of that is taxed at only 10.5%, and the rest at 17.5%. The IRD owes you the difference.

      3. You Are Eligible for the Independent Earner Tax Credit (IETC)

      The IETC is a government initiative designed to provide tax relief for middle-income New Zealanders. If your annual net income falls between $24,000 and $48,000, you are entitled to a tax credit of up to $10 per week (a maximum of $520 per year).

      If your employer’s payroll system didn’t use the specific ‘ME’ tax code, you wouldn’t have received this credit in your regular paychecks. Fortunately, Inland Revenue will automatically calculate your eligibility during the year-end wash-up and add this $520 credit directly into your refund payout.

      4. You Were on the Wrong Prescribed Investor Rate (PIR)

      Your KiwiSaver and any managed funds you hold are known as Portfolio Investment Entities (PIEs). The returns on these investments are taxed based on your Prescribed Investor Rate, which can be 10.5%, 17.5%, or 28%.

      Your PIR is based on your income over the previous two tax years. If your income dropped (for example, transitioning from full-time work to part-time study) but you forgot to update your PIR with your KiwiSaver provider, you have been overpaying tax on your investment returns. When IRD reconciles your account, they can correct this overpayment and refund the excess PIE tax you paid.

      5. You Made Charitable Donations

      This is one of the most under-utilized tax benefits in New Zealand. If you donated $5 or more to an approved New Zealand charity, a religious organization, or a school (excluding standard school fees), you can claim back exactly 33.33% of your donation as a tax credit. This isn’t processed via PAYE; you have to actively submit your receipts to the IRD, which we explain in the steps below.

      How to Check Your Refund Status via myIR (Step-by-Step)

      For most salary and wage earners, the refund process is almost entirely automated. However, you still need to log in to ensure your money actually makes it to your bank account.

      Step 1: Access Your Account

      Navigate to the Inland Revenue website and log in to your myIR portal. If you have never used myIR, you can easily register using your 9-digit IRD number.

      Step 2: Verify Your Bank Details

      Inland Revenue no longer issues cheques. If they do not have a valid, active New Zealand bank account number on file for you, your refund will sit indefinitely as a credit on your IRD account. Go to the “Profile” section and ensure your bank account details are 100% correct.

      Step 3: Review Your Income Assessment

      Starting from late May through to the end of July, IRD issues automatic income tax assessments. Click on the “Income Tax” tab for the year ending 31 March. You will see one of two statuses:

      • Refund: The calculation is complete. If your bank details are correct, the funds will be transferred to your account automatically.
      • More Information Required: IRD needs you to confirm a few details before they can release the money. This usually involves clicking a button to confirm you were a New Zealand tax resident for the full year, or declaring any minor untaxed income.

      Automatic Assessment vs. Filing an IR3: Which Are You?

      New Zealand uses a two-tier system for the end-of-year tax wash-up. Identifying which tier you belong to dictates whether you can just wait for the money, or if you need to roll up your sleeves and file paperwork.

      Filing TypeWho This Applies ToAction Required by You
      Automatic AssessmentEmployees earning a standard salary or wage, individuals whose only other income is interest from NZ banks, dividends, or KiwiSaver PIE income.Virtually none. Just log into myIR, review the automated summary, and ensure your bank account details are up to date.
      Individual Tax Return (IR3)Self-employed sole traders, independent contractors, people earning income from flatmates (outside of standard boarding rules), gig economy workers (Uber, Airbnb), or those with overseas income.You must actively calculate your income, claim your eligible business expenses, and file an IR3 return via myIR by 7 July (or later if you use an accountant).

      If you earned any money that did not have PAYE deducted before it hit your bank account—even if it was just a few thousand dollars from a weekend side hustle—you are legally obligated to file an IR3. Relying on the automatic assessment when you have untaxed business income can result in severe penalties and use-of-money interest charges down the line.

      Turnaround Times: How Long Before the Money Hits Your Account?

      Once the end of the tax year passes on 31 March, the waiting game begins. Employers have until mid-April to submit all their final payroll data to Inland Revenue.

      If you fall under the Automatic Assessment category, IRD processes these in massive batches starting in late May and running through July. Once your assessment shows as “Issued” in your myIR portal, it typically takes 3 to 5 working days for the direct credit to clear into your bank account. Do not panic if your friends or colleagues get their refunds weeks before you do; the rollout is staggered alphabetically and by processing capacity.

      If you are filing an IR3 Return, the timeline depends entirely on when you submit it. Once you click submit, it generally takes Inland Revenue 2 to 6 weeks to process manual returns, as these often require staff to briefly review claimed business expenses, home office deductions, or split-year residency indicators.

      Claiming the 33.33% Donations Tax Credit

      If you have been throwing away your donation receipts, you are quite literally throwing away free money. The New Zealand government incentivizes charitable giving by offering a massive 33.33% rebate.

      The Rules of the Rebate:

      • The donation must be $5 or more.
      • The organization must be an approved “donee organization” (which covers almost all registered NZ charities, SPCA, Salvation Army, and state schools).
      • Your total claim cannot exceed your total taxable income for the year.
      • You must have a physical or digital receipt that clearly states your name, the date, the amount, the charity’s registration number, and explicitly uses the word “donation.”

      How to Claim:

      You do not need to wait until the end of the tax year to claim this. At any point during the year, you can log into myIR, navigate to the “Donation Tax Credit” section, enter the amount, and upload a clear photo or PDF of your receipt. Inland Revenue will process this separately from your main income tax assessment, meaning you could get this cash injection much earlier in the year. Crucially, you can also backdate claims for up to four prior tax years if you have old receipts lying around.

      What If You Have a Tax Bill Instead?

      Sometimes, the end-of-year wash-up reveals that you actually owe Inland Revenue money. This is known as Residual Income Tax (RIT). This most frequently happens if you were under-taxed due to using the wrong tax code, if your employer made a payroll error, or if you received an untaxed benefit.

      If your automatic assessment results in a bill to pay, you generally have until 7 February of the following year to settle the balance. If you cannot afford to pay it as a lump sum, myIR allows you to easily set up an installment arrangement, letting you chip away at the debt with weekly or fortnightly direct debits. Ignoring a tax bill is the worst thing you can do, as Inland Revenue applies hefty late payment penalties and steep use-of-money interest rates to overdue accounts.

      Frequently Asked Questions

      Can I claim a tax refund for previous financial years?

      Yes. Inland Revenue allows you to request a reassessment or file missing returns for the past four financial years. If you realize you were on the wrong tax code back in 2023, or if you found a stack of old donation receipts, you can log into myIR, modify the specific period, and claim any overpaid tax.

      Does increasing my KiwiSaver contribution rate reduce my tax bill?

      No. Unlike some overseas retirement schemes (like the 401k in the United States), KiwiSaver contributions in New Zealand are deducted from your after-tax pay. Increasing your contribution rate from 3% to 8% will absolutely build your wealth faster, but it does not lower your taxable income or trigger a larger tax refund.

      Will my student loan or child support affect my refund payout?

      If you have a completely standard, up-to-date student loan, your tax refund will be paid out to you normally. However, if you are in arrears on your student loan, or if you owe outstanding child support payments, Inland Revenue has the legal authority to intercept your income tax refund and redirect those funds to clear your outstanding government debts first.

      Are IRD tax refunds considered taxable income?

      No. An income tax refund is simply Inland Revenue returning your own money to you because you paid too much throughout the year. It is not classified as new income, and you do not have to declare it on next year’s tax return.

      Disclaimer: This is general information, not personalized financial advice. This article provides general information and educational content only. We are not registered financial advisers. Always speak to a licensed financial advice provider.

      Date: 2/06/2026

      Author: Luca Tariciotti

    • Student Loan NZ — How Long Will It Actually Take to Pay Off?

      Student Loan NZ — How Long Will It Actually Take to Pay Off?

      Date: 20/05/2026

      Author: Luca Tariciotti

      In New Zealand, paying off a typical student loan takes around 6 to 8 years depending on your salary, but heading overseas without a plan can drag this out for over a decade and cost you thousands in interest. Understanding exactly how the Inland Revenue Department (IRD) calculates your mandatory deductions gives you the power to project your debt-free date, allowing you to decide if making voluntary extra payments is actually a smart move for your financial future.

      If you have ever stared at your payslip and wondered where a good chunk of your hard-earned money went, your student loan deduction is likely a major culprit. For many Kiwis, the student loan feels like an invisible tax that sits on our shoulders long after graduation. But here is the good news: because the New Zealand government structure keeps loans interest-free for residents, this is one of the most unique debts you will ever carry.

      Whether you are aiming to be debt-free before applying for a mortgage, starting a business, or planning a big move to London or Melbourne for your OE, you need to know exactly how long you will be shackled to this debt. Let’s break down the mandatory deduction rates, what happens when you leave the country, and whether or not those voluntary extra payments are actually worth it.

      How the IRD Calculates Your Mandatory Deductions in 2026

      The mechanics of paying off your student loan in New Zealand are incredibly straightforward once you understand the core formula. As long as you are living in Aotearoa, your student loan is completely interest-free.

      Repayments are calculated based on your income, not the total size of your loan. According to the Inland Revenue Department (IRD), for the 2026 tax year, the student loan repayment threshold remains locked at $24,128 per year (which breaks down to $464 per week or $928 a fortnight).

      If you earn under this threshold, you do not have to make any mandatory repayments. But for every single dollar you earn above that $24,128 threshold, the IRD mandates a strict 12% deduction.

      Let’s look at a few practical, real-world New Zealand dollar examples:

      • The $60,000 Salary: Your income is $35,872 above the $24,128 threshold. The IRD takes 12% of that $35,872, meaning you will pay $4,304.64 toward your loan over the year (about $82.78 per week).
      • The $85,000 Salary: Your income is $60,872 above the threshold. At 12%, you are paying $7,304.64 per year (roughly $140.47 a week).
      • The $110,000 Salary: Your income is $85,872 above the threshold. At 12%, your mandatory repayment is $10,304.64 per year (about $198.16 per week).

      Because the threshold is frozen for 2026, any pay rise you get will immediately result in more of your take-home pay being diverted to the IRD for your student loan.

      Calculate your exact student loan deductions with our free Hourly to Take-Home Pay Calculator

      The Math: How Long Will It Actually Take to Pay Off?

      To figure out how long it will take to clear your balance, simply divide your total loan amount by your yearly mandatory repayment amount. As your salary increases throughout your career, your repayment speed accelerates automatically. This is why many Kiwis find that their loan slowly chips away in their early twenties, but suddenly disappears rapidly once they hit their peak earning years.

      To give you a clearer picture, here is a breakdown of how long it takes to pay off a standard $40,000 student loan at various income levels in 2026, assuming your salary remains static:

      Annual Salary (NZD)Income Above ThresholdYearly Student Loan Repayment (12%)Time to Pay Off $40,000 Loan
      $50,000$25,872$3,104.6412.9 Years
      $65,000$40,872$4,904.648.1 Years
      $80,000$55,872$6,704.645.9 Years
      $95,000$70,872$8,504.644.7 Years
      $110,000$85,872$10,304.643.8 Years
      $130,000$105,872$12,704.643.1 Years

      The table above gives you a rough baseline, but everyone’s situation is unique. If you want to see your exact timeline, punch your current balance and salary into our free Student Loan Repayment Calculator NZ to get your personalized debt-free date.

      Note: This table assumes you are a New Zealand resident for tax purposes, your loan remains interest-free, and you have a single source of income.

      The Overseas Trap: Interest Rates and Obligations

      Everything changes the moment you pack your bags for a standard Overseas Experience (OE) or a permanent move to Australia or further abroad. If you leave New Zealand for more than 183 consecutive days (about six months), you become an “overseas-based borrower.”

      The two massive financial changes are:

      1. You are charged interest. For the 2026-2027 tax year, the annual interest rate applied to overseas borrowers is hovering around 5.6%.
      2. Your repayments are based on your loan balance, not your income. The IRD does not care if you are making £80,000 in London or pouring pints in a Melbourne pub for minimum wage. When you are overseas, your mandatory minimum repayments are fixed based on how much you owe.

      For example, if your loan is between $15,000 and $30,000, you are legally required to pay $2,000 per year (usually split into two instalments due in September and March). If your loan is between $30,000 and $45,000, your mandatory repayment jumps to $3,000 per year.

      The Danger of the Minimum Payment

      If you have a $40,000 student loan and move to Australia, you are required to pay $3,000 a year. However, at a 5.6% interest rate, your loan is silently racking up $2,240 in interest over those 12 months. This means out of your $3,000 mandatory payment, only $760 is actually touching the principal debt. If you only pay the minimum, a $40,000 loan will take decades to clear and cost you thousands in interest.

      If you are moving overseas, it is absolutely crucial to make voluntary extra payments to beat the interest rate, or better yet, aggressively pay the loan down before your flight departs. You can use independent financial platforms like Sorted.org.nz to calculate exactly how much extra you need to contribute to actually pay down the principal while living abroad.

      Should I Make Voluntary Extra Payments in NZ?

      One of the most common questions young Kiwis ask is: “Should I put my spare cash toward my student loan to pay it off faster?”.

      Mathematically speaking, if you plan to stay in New Zealand, the answer is almost always no.

      Because the NZ student loan is interest-free for residents, there is zero financial benefit to paying it off early. In fact, inflation actually erodes the real value of your debt over time. Let’s say you have a spare $100 a week. You have two options:

      • Option A: You put $100 extra into your student loan as a voluntary payment. You pay off your debt faster, but you earn zero return on that money.
      • Option B: You put $100 a week into a high-interest savings account (currently yielding around 5%) or increase your KiwiSaver contributions. Over five years, that $100 a week grows exponentially thanks to compound returns.

      Financially, keeping the cash and investing it is the smarter move. The only exception to this rule is if the debt is causing you severe mental stress, or if you are planning to move overseas and want to avoid the upcoming 5.6% interest penalty. In those specific scenarios, throwing extra cash at the IRD makes perfect sense.

      Secondary Tax and Your Student Loan

      Taking on a side hustle, weekend gig, or a second job is a fantastic way to accelerate your financial goals, but you need to be prepared for how the IRD treats your secondary income.

      When you have a primary job that pays over the $24,128 threshold, your main employer is already accounting for your tax-free threshold. This means your second job will use a secondary tax code—usually STC, ST, or CAE depending on your total income bracket.

      Crucially, because your first job has already used up your student loan repayment threshold, every single dollar you earn at your second job will be subjected to the 12% student loan deduction.

      For example, if you earn $200 a week bartending on the weekends as a second job, you will immediately lose $24 of that to your student loan, on top of your standard PAYE tax. It can make a second job feel less rewarding in the short term, but the silver lining is that it aggressively speeds up your debt-free date.

      What If I Become a Contractor or Self-Employed?

      If you decide to leave the traditional 9-to-5 grind and become a sole trader, freelancer, or contractor, your student loan obligations do not disappear. However, the way you pay them changes completely.

      When you are an employee, your boss handles the PAYE and student loan deductions before the money even hits your bank account. When you are self-employed, you are entirely responsible for calculating and paying your own 12% student loan deduction on your net profit (your income minus your business expenses) at the end of the financial year.

      This can catch many new contractors off guard. If your contracting business makes $80,000 in profit, you will suddenly owe the IRD a lump sum of roughly $6,700 just for your student loan when tax time rolls around. It is absolutely critical to set aside 12% of all your earnings above the $24,128 threshold into a separate bank account throughout the year so you aren’t hit with a massive, unexpected tax bill in March.

      Does a Student Loan Affect Buying a House?

      Yes, significantly. A very common misconception is that because the loan is interest-free, banks do not care about it. In reality, New Zealand banks care heavily about your cash flow and your uncommitted monthly income when assessing your home loan application.

      When reviewing your mortgage application, banks adhere strictly to regulations set by the Reserve Bank of New Zealand (RBNZ), including Loan-to-Value Ratios (LVR) and Debt-to-Income (DTI) restrictions. Your student loan negatively impacts your mortgage application in two main ways:

      1. Reduced Servicing Ability: Because 12% of your income above the threshold is diverted straight to the IRD, you have less take-home pay available. Banks stress-test your mortgage application at interest rates much higher than the current market rate. Having 12% of your income already locked up makes it harder to pass these rigorous stress tests.
      2. Debt-to-Income (DTI) Ratios: Under the RBNZ DTI rules, your total debt (which includes your student loan, credit cards, car loans, and the proposed mortgage) cannot exceed a certain multiple of your gross income. A large student loan eats directly into the total amount of debt you are allowed to take on, meaning it directly lowers your maximum borrowing power for a property.

      Nearing the Finish Line: Don’t Overpay

      When your student loan balance drops below a few thousand dollars, you need to pay close attention to your payslips. Your employer’s payroll software does not automatically know your total loan balance; it simply continues to blindly deduct 12% of your pay based on your declared tax code.

      If your balance is $500, but your standard pay cycle deducts $300 a fortnight, you will overpay your loan in less than a month. To avoid giving the government an interest-free loan of your own money, you can apply for a Special Deduction Rate (SDR) through your myIR account when you are very close to paying it off.

      Once the loan hits zero, you must inform your employer immediately to change your tax code (usually from “M SL” to just “M”) so you can finally enjoy that extra cash in your take-home pay. Do not assume the IRD will automatically notify your boss—it is your responsibility to update your tax code paperwork.

      Frequently Asked Questions

      What is the current NZ student loan repayment threshold?

      For the 2026 tax year, the repayment threshold is $24,128 per year (or $464 per week). You do not pay anything if you earn under this amount, but you will pay 12% on every dollar earned above it.

      Does my student loan affect my ability to get a mortgage in NZ?

      Yes. While banks do not charge interest on your student loan, they factor it in when calculating your debt-to-income (DTI) ratio and your uncommitted monthly income. Because 12% of your income above the threshold is taken by the IRD, banks see this as less money available to service a mortgage, which will slightly reduce your maximum borrowing power.

      Do I pay interest on my student loan?

      If you live in New Zealand for more than 183 days a year, your student loan is completely interest-free. If you move overseas for longer than six months, interest is applied. For the 2026-2027 tax year, the overseas interest rate is 5.6%.

      Can I stop my student loan deductions if I need extra cash?

      Generally, no. The 12% deduction is a strict legal requirement. The only way to stop deductions is if your income drops below the $24,128 threshold, or if you apply directly to the IRD for a significant financial hardship exemption, which is assessed on a strict case-by-case basis.

      What happens if I forget to pay my minimums while overseas?

      The IRD applies steep penalties. On top of the standard 5.6% interest, late payment interest is currently set at 9.6% annually for the 2026 tax year. This will cause your debt to spiral rapidly, and the IRD can even stop you from leaving New Zealand at the border if your defaults are significant enough.

      Ready to see exactly how a second job or side hustle will impact your take-home pay and student loan? 👉 Check this with our New Zealand Secondary Tax Calculator.

      Disclaimer: This is general information, not personalized financial advice. For specific guidance regarding your student loan obligations, tax codes, or financial planning, please consult the Inland Revenue Department (IRD) or a registered financial adviser.

    • Secondary Tax in NZ — Everything You Need to Know for Your Second Job

      Secondary Tax in NZ — Everything You Need to Know for Your Second Job

      Date: 19/05/2026

      Author: Luca Tariciotti

      Secondary tax isn’t a penalty rate; it’s simply the normal PAYE system applying your correct top tax bracket to your second job so you don’t end up with a massive tax bill at the end of the year. With the cost of living pushing many Kiwis to pick-up side hustles, weekend shifts, or freelance work, understanding how your extra income is taxed ensures every dollar you earn actually moves you forward.

      Let’s break down how secondary tax codes work in New Zealand, clear up the biggest misconceptions, and help you figure out exactly what code to give your employer.


      The Biggest Myth About Secondary Tax in NZ

      If you talk to anyone in the lunchroom about getting a second job, you’ll inevitably hear someone say: “Don’t bother, the secondary tax will take half your wages.” This is the single biggest misconception about secondary tax in New Zealand.

      Secondary tax is not a penalty. The Inland Revenue Department (IRD) does not punish you for working two jobs. New Zealand operates on a progressive tax system, which means your income is taxed in layers (brackets). As your overall income increases, only the dollars that fall into the higher brackets are taxed at a higher percentage.

      When you get a second job, your primary employer has already used up your lower tax brackets (like the 10.5% and 17.5% layers). Therefore, your secondary employer needs to tax your second income at your “marginal” tax rate—the highest rate that applies to your total combined annual income. If they didn’t do this, you would underpay tax all year and receive a giant, painful bill from the IRD come April.

      2026 NZ Income Tax Brackets Refresher

      To understand secondary codes, you first need to understand the standard tax brackets for the 2025/2026 tax year:

      • 10.5% on income up to $15,600
      • 17.5% on income from $15,601 to $53,500
      • 30% on income from $53,501 to $78,100
      • 33% on income from $78,101 to $180,000
      • 39% on income over $180,000

      Your main job (using an M or ME tax code) automatically accounts for these progressive layers. Your second job needs a specific code to pick up right where your main job leaves off.


      How to Find Your Secondary Tax Code

      Your secondary tax code is based entirely on your estimated total annual income from all sources. Here are the standard secondary tax codes for New Zealand employees:

      • SB: Use if your total expected income is $15,600 or less. (Taxed at 10.5%).
      • S: Use if your total expected income is between $15,601 and $53,500. (Taxed at 17.5%).
      • SH: Use if your total expected income is between $53,501 and $78,100. (Taxed at 30%).
      • ST: Use if your total expected income is between $78,101 and $180,000. (Taxed at 33%).
      • SA: Use if your total expected income is over $180,000. (Taxed at 39%).

      (Note: If you have a New Zealand Student Loan, you simply add “SL” to your code, such as S SL or SH SL. This tells your employer to deduct the mandatory 12% student loan repayment from your secondary income).

      Check our New Zealand Secondary Tax Calculator and Student Loan Repayment Calculator NZ.

      Real NZ Dollar Examples

      Let’s look at how this plays out in the real world with some NZD examples.

      Example 1: The Part-Time Hustle Mark works part-time at a local supermarket, earning $35,000 a year. He decides to pick up a second part-time job at a hardware store, which will pay him roughly $10,000 a year.

      • Main Job: $35,000 (Uses code M)
      • Second Job: $10,000
      • Total Expected Income: $45,000 Because his total income ($45,000) falls into the $15,601 to $53,500 bracket, Mark will give the hardware store the S tax code. His hardware store earnings will be taxed at a flat 17.5%.

      Example 2: Pushing into a Higher Bracket Jane is a graphic designer earning $70,000 a year at her primary agency. She decides to work weekends managing social media for a local cafe, which pays her $15,000 a year.

      • Main Job: $70,000 (Uses code M)
      • Second Job: $15,000
      • Total Expected Income: $85,000 Because her total combined income ($85,000) pushes past the $78,100 threshold, she falls into the 33% tax bracket. Jane must use the ST tax code for her cafe job. Every dollar she earns at the cafe will be taxed at 33%.

      Special Tax Codes: STC and CAE

      Sometimes, the standard secondary codes don’t perfectly fit your situation. That’s where special codes come in.

      1. Tailored Tax Code (STC) If you think your secondary tax code will result in you overpaying tax during the year (for example, if your second job only pushes your total income slightly into the next tax bracket, rather than fully), you can apply for a Tailored Tax Code directly through the IRD. Formerly known as a Special Tax Code (STC), this allows the IRD to calculate a custom percentage for your secondary employer to deduct, ensuring your PAYE is perfectly balanced.

      2. Casual Agricultural Worker (CAE) If you are doing casual, seasonal agricultural work (like fruit picking, shearing, or shed-handling) for up to 3 months, you use the CAE tax code. This taxes your earnings at a flat rate of 17.5%, plus ACC levies.


      Contractor vs Employee NZ: How It Affects Your Second Job

      Often, picking up a second stream of income isn’t about finding a second employer—it’s about freelancing or starting a small business. You might be weighing the debate of contractor vs employee NZ and asking yourself: should I go contracting NZ for my side hustle?

      If you choose to be an employee, everything is handled for you via the PAYE system and the secondary codes we just discussed. Your employer deducts your tax, ACC, and KiwiSaver before the money hits your bank account.

      If you choose to be a contractor, the rules change:

      • Tax Codes: You won’t use S, SH, or ST codes. Instead, you’ll generally use the WT (Withholding Tax) tax code for Schedular Payments. The tax rate deducted depends on your specific industry (often ranging from 10% to 20%), but this is only a pre-payment.
      • Your Responsibilities: As a contractor, you are running your own business. You are responsible for paying your own ACC levies, setting aside money for your student loan, and managing your own KiwiSaver contributions.
      • Expenses: The major benefit of contracting is that you can claim business expenses (like home office costs, software, or travel) against your contracting income, which lowers your overall taxable income.

      Whether you should go contracting in NZ depends heavily on how comfortable you are with accounting, managing your own cash flow, and setting aside money for the IRD at the end of the financial year.


      What Happens If You Get Your Code Wrong?

      If you accidentally give your secondary employer the wrong tax code, one of two things will happen:

      1. You Overpay: If you give a code that taxes you at 33% (ST), but your total income actually keeps you in the 17.5% bracket, you will overpay tax every payday. The good news? The IRD automatically calculates this at the end of the tax year (March 31) and will issue you a tax refund between May and July.
      2. You Underpay: If you give a code that taxes you at 17.5% (S), but your total income pushes you into the 30% bracket, you will underpay tax. At the end of the tax year, the IRD will calculate the shortfall and send you a bill that you are legally required to pay.

      Always estimate your total income cautiously. It is far better to slightly overpay and get a nice refund in the winter than to underpay and scramble to find cash to pay the taxman.


      Frequently Asked Questions

      1. Do I get taxed more heavily just because I have a second job? No. You are taxed on your total income. Earning $60,000 from one job results in the exact same amount of total tax as earning $40,000 from your main job and $20,000 from a second job. The secondary tax code just ensures the correct rate is applied to your top-up income.

      2. How do I change my secondary tax code if my income drops? If your primary salary drops or you reduce your hours, your total estimated income might fall into a lower bracket. Simply fill out a new Tax Code Declaration (IR330) form, hand it to your secondary employer, and they will update your code in their payroll system.

      3. Do I need a secondary tax code if I’m a sole trader/contractor? If you are invoicing clients directly as a sole trader (not receiving schedular payments), you do not use secondary tax codes like SH or ST. You receive the full gross amount from your clients and must calculate, declare, and pay your own income tax at the end of the year via an IR3 tax return.

      4. What code do I use if both my jobs pay exactly the same amount? You can only have one “main” job. Choose whichever job you have held the longest, or whichever is most stable, and assign that the M code. Give the other job the appropriate secondary code based on your combined total income.


      Disclaimer: This is general information, not personalised financial advice. For advice specific to your situation, we recommend speaking with a registered tax agent or accountant, and always checking the latest updates on the Inland Revenue Department (IRD) and Sorted.org.nz websites.

    • Contractor vs Employee in NZ — The Real Financial Difference

      Date: 18/05/2026

      Author: Luca Tariciotti

      If you are weighing up being a contractor vs employee in NZ, you might think jumping from a $100k salary to an $80-an-hour rate is an instant ticket to wealth. But once you strip away the hidden costs of unpaid leave, ACC levies, and business expenses, the real financial difference is much smaller than it appears.

      With the cost of living in Wellington and Auckland remaining high in 2026, many Kiwis are looking for ways to maximize their income. The allure of contracting is undeniable. You set your own hours, you can pick and choose your clients, and the hourly rates look incredibly high compared to a standard PAYE salary. But there is a massive difference between what you invoice as a business and what you actually get to keep in your personal bank account.

      If you are currently wrestling with the contractor vs employee in NZ dilemma, you are absolutely not alone. It is one of the most common career questions we encounter. This comprehensive guide will break down exactly what that choice means for your back pocket. We are going to put two realistic scenarios head-to-head: a standard $100,000 employee salary versus an $80 per hour contractor rate. We will look at the hidden costs like holidays, insurance, accounting software, and what happens to your KiwiSaver.

      By the end of this guide, you will know exactly whether you should go contracting in NZ, or if the safety and perks of the standard PAYE system are the better bet for you.

      The Legal and Practical Differences

      Before we dive into the spreadsheets and crunch the numbers, it is crucial to understand how New Zealand employment law and the Inland Revenue Department (IRD) view these two very different ways of working. You cannot simply call yourself a contractor to pay less tax; there are legal definitions you must meet.

      The Employee (The PAYE Safety Net)

      When you are an employee, you operate under an employment agreement covered by the Employment Relations Act. Your employer handles all the heavy lifting. They deduct your tax (PAYE), sort out your student loan repayments, manage your KiwiSaver contributions (and add their 3% minimum match), and pay your ACC earner’s levy before the money even hits your bank account.

      Most importantly, you get guaranteed statutory rights:

      • Four weeks of paid annual leave.
      • 12 statutory public holidays (including Matariki).
      • A minimum of 10 days paid sick leave per year.
      • Protection against unjustified dismissal.

      The Contractor (The Independent Hustle)

      As a contractor, you are essentially running your own business—even if you are just a sole trader. You are an independent entity providing a service to a client. You invoice them for your time or the completed project, and they pay you the gross amount (plus GST, if you are registered).

      The IRD uses specific tests to determine if you are genuinely a contractor, including the Control Test (do you have the freedom to choose how and when you work?), and the Independence Test (do you provide your own tools and work for multiple clients?).

      As a contractor, it is entirely on your shoulders to set aside money for tax, pay your own ACC levies, fund your own retirement, and cover all your own expenses. If you don’t work, you don’t get paid. There is zero sick leave and zero holiday pay.

      The Real Numbers: $100k Salary vs $80/hr Contractor

      To make this practical, we are going to use a real-world worked example. Let’s compare a standard $100,000 permanent employee salary with an independent contractor charging $80 an hour. At first glance, $80 an hour sounds like vastly more money. But let’s look at the reality of billable hours and necessary downtime.

      The $100,000 Employee Scenario

      If you are on a $100k salary, you are paid for 52 weeks of the year, regardless of when you take your summer holiday or if you catch a nasty winter flu.

      A standard working year is 260 days (52 weeks x 5 days, or 2,080 hours). However, because of your guaranteed time off (20 days annual leave, 12 public holidays, 10 sick days), you are effectively “at work” for only 218 days, or 1,744 hours.

      Using the 2026 NZ tax brackets (which took full effect in July 2024), here is how a $100,000 salary breaks down:

      Income & DeductionsAmount (NZD)
      Gross Income$100,000
      Income Tax-$22,877
      ACC Earner’s Levy (approx 1.39%)-$1,390
      Take-Home Pay (Before KiwiSaver)$75,733

      The Hidden Bonus: Your employer is legally required to contribute 3% to your KiwiSaver. That is an extra $3,000 (before Employer Superannuation Contribution Tax) going straight into your retirement fund every single year. According to Sorted.org.nz, this “free money” is a massive factor in long-term wealth building.

      The $80/hr Contractor Scenario

      Now let’s look at the contractor. You charge $80 an hour. If you worked 40 hours a week for 52 weeks straight, you would invoice $166,400. That sounds incredible!

      But you are human. You need a break. Let’s assume you take the exact same time off as the employee: 4 weeks of holiday, the 12 statutory public holidays, and 10 sick days.

      • Total Billable Hours: 1,744 hours
      • Gross Invoiced Income (1,744 hours x $80): $139,520

      So, the contractor brings in roughly $39,500 more in gross cash than the employee. But we haven’t deducted the expenses of running a business yet.

      Check our Contractor vs Employee Calculator NZ.

      The Hidden Costs of Being Your Own Boss

      When you are self-employed, a chunk of your gross income goes straight toward overheads that an employer usually covers for free. Let’s break down the realistic, conservative business expenses for our $80/hr contractor over a year:

      • Insurance: Most corporate clients will require you to hold Professional Indemnity and Public Liability insurance before you can sign a contract. Let’s estimate this at $1,200/year.
      • Accounting & Software: You’ll need software like Xero or Hnry, or an accountant to manage your taxes and file GST returns accurately. Let’s budget $1,000/year.
      • Technology & Equipment: A good laptop, software subscriptions (like Adobe or Microsoft 365), and general IT maintenance. Let’s call it $1,500/year.
      • Home Office & Connectivity: A portion of your home internet, mobile phone plan, and home office utility costs. Let’s say $1,000/year.
      • ACC Levies: Contractors pay the standard earner’s levy plus the work account levy (CoverPlus or CoverPlus Extra), which varies by industry risk. Let’s estimate $2,200/year.

      Total Estimated Expenses: $6,900/year.

      Your taxable profit is now $139,520 minus $6,900 = $132,620.

      Tax Time: IRD Brackets, Provisional Tax, and GST

      Let’s look at how the income tax shakes out for the contractor’s $132,620 taxable profit, using the standard 2026 NZ tax rates (10.5% up to $15.6k, 17.5% up to $53.5k, 30% up to $78.1k, and 33% up to $180k).

      The total income tax on $132,620 is roughly $33,640.

      Contractor Final Take-Home Math:

      • Gross Profit: $132,620
      • Minus Income Tax: -$33,640
      • Minus KiwiSaver (Matching the employee’s 3% + your own 3% to keep things even = $6,000)
      • Net Money in the Bank (After equivalent retirement savings): ~$92,980

      The Provisional Tax Trap

      If your tax bill at the end of the year is more than $5,000, the IRD will require you to pay “Provisional Tax” the following year. This means you will be paying tax in advance in three installments throughout the year, while simultaneously paying off your tax bill from your first year of contracting. Many new contractors get caught out by this double-whammy in year two. You must be disciplined in setting aside at least 30% of every invoice into a separate tax bank account.

      A Note on GST (Goods and Services Tax)

      If you earn over $60,000 in a 12-month period as a contractor, the IRD requires you to register for GST. This means you must add 15% to your hourly rate. If your rate is $80/hr, you will actually invoice $92/hr ($80 + GST). You collect that extra $12 and hold it, then pass it on to the IRD every 1, 2, or 6 months. It is not your money, so never spend it.

      As a contractor, you miss out entirely on the 3% employer KiwiSaver match, because you are your own employer. However, you can (and should) make voluntary contributions. As long as you personally contribute at least $1,042.86 before June 30th each year, you still qualify for the annual Government contribution of up to $521.43.

      If you have a New Zealand Student Loan, employees have a flat 12% deducted from their pay for anything earned over the repayment threshold (currently $24,128 per year). As a contractor, this isn’t deducted automatically. You must calculate this 12% on your net profit above the threshold and pay it directly to the IRD at the end of the tax year. Failing to budget for this is a common mistake that leads to massive unexpected tax bills.

      The “Risk Premium”: How Much Should You Charge?

      Looking at the numbers above, the contractor clears around $92k (after funding their own retirement and business expenses), while the employee clears around $75k (but gets employer KiwiSaver on top). The contractor is financially ahead, but only by roughly $15,000 to $17,000 a year.

      Is $15,000 enough of a reward for the extra stress? That is what we call the Risk Premium.

      When you ask, “should I go contracting NZ?”, you have to factor in the risks the math doesn’t show:

      • Job Insecurity: A contractor can usually be let go with zero to two weeks’ notice. If the economy tightens, as seen in recent RBNZ updates, contractors are often the first overhead businesses cut.
      • Bench Time: We assumed you work 1,744 billable hours. But what if it takes you a month to find your next contract? That’s roughly $13,000 in lost revenue.
      • Admin Time: You will spend unpaid hours chasing late invoices, filing taxes, and finding new clients.

      The Golden Rule of Contracting: A common rule of thumb in New Zealand is that your hourly contracting rate needs to be at least your desired salary divided by 1,000 (or 1,200 at a stretch) to break even on the risk and expenses. So, to match a comfortable $100k salary lifestyle with all its protections, an $80 to $100 hourly rate is exactly where you need to be.

      Ultimately, if you are highly disciplined with money, have an in-demand skill set, and value flexibility over predictability, contracting can be highly lucrative. If you value security, easy mortgage approvals, and paid sick leave, stick with PAYE.


      Frequently Asked Questions

      What is the difference between a contractor and an employee in NZ?

      An employee has a legal employment agreement, receives guaranteed pay, paid leave, and job security. Their employer handles tax, ACC, and KiwiSaver. A contractor is self-employed, runs their own business, invoices for their time, handles their own taxes and expenses, and receives no paid leave or job security.

      Do contractors pay ACC in New Zealand?

      Yes, contractors actually pay more in ACC than employees. While employees only pay the Earner’s Levy (deducted via PAYE), contractors must pay the Earner’s Levy plus a Work Account levy (CoverPlus), which covers workplace injuries. The rate depends on the risk level of your specific industry.

      Can a contractor get KiwiSaver in NZ?

      Contractors can voluntarily contribute to KiwiSaver. However, you do not receive the 3% employer match, because you are your own employer. You are still eligible for the annual Government contribution (up to $521.43) as long as you personally contribute at least $1,042.86 before June 30th each year.

      How much extra should a contractor charge compared to an employee?

      A standard NZ rule of thumb is to take the annual permanent salary you want and divide it by 1,000. For example, to comfortably match a $100,000 salary with its benefits and absorb the risks of unpaid downtime and business expenses, you should aim to charge around $100 per hour (or at minimum $80/hr).

      What expenses can I claim as a contractor in NZ?

      You can claim expenses directly related to generating your income. Common deductions include accounting fees, professional insurance, a portion of your home office costs (power, internet, rent/mortgage interest based on floor space), mobile phone bills, and travel expenses to client sites (excluding your normal daily commute).


      Disclaimer: This is general information, not personalised financial advice. Tax laws and rates are subject to change, and individual circumstances vary. Always consult with a registered accountant or financial adviser regarding your specific situation.

    • How to Calculate Your Take-Home Pay in NZ (PAYE, ACC, KiwiSaver Explained)

      Knowing exactly how much lands in your bank account on payday helps you budget better and figure out how much you can really afford for a mortgage, rent, or those shared flatmate expenses. With the cost of living across New Zealand climbing, understanding the difference between your gross salary and your actual take-home pay after PAYE, ACC, and KiwiSaver is crucial for your daily financial survival.

      Introduction

      Kia ora! We’ve all been there: you sign an employment contract for a shiny new salary, say $80,000, and you feel on top of the world. But when that first payday rolls around and you check your banking app, the number hitting your account looks a lot smaller than you expected. Where did it all go?

      Whether you are trying to budget for your weekly Pak’nSave run, save up for a first home deposit, or you just want to figure out “how much tax do I pay in NZ?”, you need to understand the mechanics of your payslip. Specifically, you need to understand the “Big Three” deductions that are stripped out of your paycheck automatically: PAYE (income tax), the ACC earners’ levy, and your KiwiSaver contributions.

      In New Zealand, the Inland Revenue Department (IRD) system is designed to take these deductions out before you even see the money. That’s great for convenience—you rarely have to worry about a massive, unexpected tax bill at the end of the financial year—but it can make it incredibly confusing to know exactly what your true take-home (net) pay is.

      To clear up any confusion regarding old tax years, we are going to break down every single deduction line by line using the absolute latest April 1, 2026 legislative updates. We will use real New Zealand dollar examples for $60,000, $80,000, and $100,000 salaries so you know exactly where your hard-earned money is going in the current financial landscape.

      1. PAYE Income Tax: How New Zealand’s Tax Brackets Actually Work

      PAYE stands for “Pay As You Earn.” It is exactly what it sounds like: as you earn money on your hourly wage or salary, your employer calculates a slice of it and sends it directly to the IRD on your behalf.

      A massive misconception in New Zealand is how our tax brackets actually work. We use a progressive tax system. This means that as you earn more, you do not pay the highest tax rate on all of your money. You only pay the higher rate on the money that falls into that specific tier.

      Think of it like filling up a series of water buckets. The IRD only takes a 10.5% scoop out of your first bucket. Once that bucket overflows into the next, they take a slightly larger 17.5% scoop out of the second bucket, and so on.

      Here are the official, current IRD tax brackets for the 2026 tax year:

      Income RangeTax Rate
      $0 to $15,60010.5%
      $15,601 to $53,50017.5%
      $53,501 to $78,10030%
      $78,101 to $180,00033%
      $180,001 and over39%

      Let’s look at a real-world example of marginal tax:

      If you get a promotion that pushes your salary from $75,000 to $80,000, you don’t suddenly pay 33% tax on your entire $80,000 salary. You still pay the lower 10.5%, 17.5%, and 30% rates on the bottom chunks of your income. You only pay the 33% rate on the final $1,900 that “spills over” the $78,100 threshold.

      This means a pay rise is always a good thing. You will never take home less money just because you jumped into a higher tax bracket!

      2. The ACC Earners’ Levy: Your Built-In Insurance

      Next up on your payslip is the ACC levy. The Accident Compensation Corporation (ACC) is New Zealand’s unique, no-fault accidental injury scheme. It covers your medical bills, rehabilitation, and up to 80% of your lost wages if you get injured—whether you’re hurt on a construction site in Auckland, or you simply roll your ankle playing weekend social netball in Wellington.

      Because every single person in the country benefits from this safety net, every working Kiwi chips in to fund it through the ACC earners’ levy.

      The April 2026 Update:

      As of April 1, 2026, the ACC earners’ levy increased from 1.67% to 1.75% (which works out to $1.75 per $100 you earn). It is important to note that this levy is capped. For the 2026 year, you only pay the ACC levy on earnings up to a maximum threshold of $156,641. So, the absolute maximum you will ever pay for the ACC earners’ levy in a year is $2,741.22.

      While it might feel annoying to see another chunk of money disappear from your pay before it reaches your bank, ACC is a massive nationwide safety net that prevents everyday Kiwis from going bankrupt over unexpected hospital bills.

      3. KiwiSaver: Paying Your Future Self

      The third major deduction is KiwiSaver, New Zealand’s voluntary retirement and first-home savings scheme. While technically voluntary, you are automatically enrolled when starting a new job, and staying in the scheme is universally considered one of the smartest financial moves you can make to combat the New Zealand retirement gap.

      The April 2026 Update:

      A major legislative shift occurred on April 1, 2026. The minimum default contribution rate for both employees and employers increased from 3% to 3.5%.

      This means a minimum of 3.5% of your gross pay is funneled into your chosen KiwiSaver fund. The beautiful part? Your employer is legally required to match that 3.5%. That is literally free money working for your retirement or your first home deposit. (Note: Employees can apply for a temporary rate reduction to stay at 3% if needed, but for long-term wealth, the new default is recommended).

      On top of employer matches, the government chips in an annual “Government Contribution.” Historically this was up to $521.43, though recent 2025/2026 tweaks reduced this to $260.72 for some, and removed it entirely for those earning over $180,000.

      You can choose to voluntarily contribute more to hit your goals faster (common rates are 4%, 6%, 8%, or 10%), but for our baseline take-home pay calculations below, we will assume you are on the new 2026 default rate of 3.5%.

      4. Line-by-Line Salary Breakdowns: The Real Math

      Let’s put all these theories into practice and see what happens to real New Zealand salaries.

      For the tables below, we will use the standard M tax code (which assumes this is your main job), and we will assume you have no student loan. We are utilizing the progressive 2026 tax brackets, the new 1.75% ACC levy, and the new 3.5% default KiwiSaver rate.

      Example 1: Earning $60,000 a Year

      Earning $60,000 is a common milestone for young professionals and tradespeople. Here is exactly where your money goes.

      Deduction TypeAnnual AmountNotes
      Gross Income$60,000.00Before any deductions.
      Income Tax (PAYE)-$10,220.5010.5% on first $15.6k, 17.5% on next $37.9k, 30% on final $6.5k.
      ACC Levy (1.75%)-$1,050.00Mandatory injury cover (calculated as 1.75% of $60,000).
      KiwiSaver (3.5%)-$2,100.00Invested for your future (calculated as 3.5% of $60,000).
      Net Take-Home Pay$46,629.50What you actually keep.
      • Monthly: $3,885.79
      • Fortnightly: $1,793.44
      • Weekly: $896.72

      Notice that out of a $60,000 gross salary, you are taking home around $896 a week to cover your rent, groceries, power, and lifestyle.

      Example 2: Earning $80,000 a Year

      Moving up the ladder to $80,000 pushes a tiny sliver of your income into the 33% tax bracket.

      Deduction TypeAnnual AmountNotes
      Gross Income$80,000.00Before any deductions.
      Income Tax (PAYE)-$16,277.50Includes 33% tax on the final $1,900 over the $78,100 threshold.
      ACC Levy (1.75%)-$1,400.00Mandatory injury cover.
      KiwiSaver (3.5%)-$2,800.00Invested for your future.
      Net Take-Home Pay$59,522.50What you actually keep.
      • Monthly: $4,960.20
      • Fortnightly: $2,289.32
      • Weekly: $1,144.66

      You earn $20,000 more on paper than the $60k earner, but due to the progressive tax system, your weekly take-home pay only goes up by about $247.

      Example 3: Earning $100,000 a Year

      Hitting six figures is a massive goal. At this level, a solid $21,900 chunk of your income sits in the 33% tax bracket.

      Deduction TypeAnnual AmountNotes
      Gross Income$100,000.00Before any deductions.
      Income Tax (PAYE)-$22,877.50Progressive tax up to the 33% tier.
      ACC Levy (1.75%)-$1,750.00Mandatory injury cover.
      KiwiSaver (3.5%)-$3,500.00Invested for your future.
      Net Take-Home Pay$71,872.50What you actually keep.
      • Monthly: $5,989.37
      • Fortnightly: $2,764.32
      • Weekly: $1,382.16

      Even on a $100k salary, after tax, ACC, and investing 3.5% into your KiwiSaver, your weekly household budget has just under $1,400 to work with.

      5. Got a Student Loan? (The Hidden Tax)

      If you went to university or completed a trade course and racked up a StudyLink loan, you have one more major hurdle before you get to your net pay.

      In New Zealand, student loan repayments are mandatory once you earn over the annual repayment threshold. For 2026, the threshold sits firmly at $24,128 per year (which breaks down to exactly $464 per week).

      The IRD will automatically deduct 12% of every single dollar you earn above this threshold.

      Let’s look at the math: If you earn $60,000, you are earning $35,872 above the threshold. That means an extra $4,304.64 a year ($82.78 a week) comes out of your pay before you see it. When you use an NZ take-home pay calculator, always make sure to tick the “Student Loan” box and use the M SL tax code. It makes a surprisingly large dent in your weekly cash flow!

      6. What If You Have a Second Job or Go Contracting?

      The standard calculations above are perfect if you have one main job as a traditional salaried employee. But life in NZ is rarely that simple. Cost of living often dictates side incomes.

      Working a Side Hustle?

      If you pick up weekend shifts at a cafe, do some freelance graphic design, or drive for Uber on top of your main 9-to-5, you will need to use a secondary tax code (like SB, S, SH, or ST). Many people think “secondary tax” means you are heavily penalized and arbitrarily taxed at a ridiculously high rate. You aren’t!

      Secondary tax codes simply try to accurately estimate what your total combined annual income will be across all your jobs, so you pay the correct progressive rate and don’t end up with a massive tax bill in March.

      Curious about the exact math? Check out our Secondary Tax Calculator to see exactly how your side hustle income is taxed.

      Thinking of Going Freelance?

      If you are weighing up a $100k salary versus an $80/hour contracting gig, the take-home math completely changes. Contractors do not get holiday pay, sick leave, or mandatory employer KiwiSaver matches. However, they can claim valid business expenses (like laptops, home office space, and vehicle mileage) to lower their overall taxable income.

      Run the numbers on our Contractor vs Employee Calculator to see which path actually leaves you with more cash in the bank.

      Frequently Asked Questions

      What is an NZ take home pay calculator used for?

      A take-home pay calculator (often called a PAYE calculator) does all the heavy math for you. You punch in your gross salary, select your KiwiSaver rate, and check if you have a student loan. It instantly calculates exactly how much cash will land in your bank account weekly, fortnightly, or monthly. It’s an essential tool for budgeting, planning for a mortgage, or negotiating a new salary in New Zealand.

      How much tax do I pay in NZ if I earn $70,000?

      If you earn $70,000 in 2026, your progressive PAYE income tax is $13,277.50. You will also pay $1,225 in ACC levies (at the new 1.75% rate), and if you contribute the default 3.5% to KiwiSaver, that’s another $2,450. Your total net take-home pay would be $53,047.50 for the year.

      Why did my take-home pay change in April 2026?

      Two big changes hit payrolls on April 1, 2026. First, the ACC earners’ levy increased to $1.75 per $100 (1.75%). Second, the minimum default KiwiSaver contribution rate for both employees and employers jumped from 3% to 3.5%. Both of these factors slightly reduced the immediate, in-hand take-home pay for everyday Kiwis, though the KiwiSaver bump means your employer is contributing more to your future wealth!

      Is KiwiSaver calculated before or after tax?

      KiwiSaver contributions are calculated based on your gross pay (your income before any tax is removed). If you earn $1,000 a week before tax, a 3.5% KiwiSaver deduction will be exactly $35. It is not calculated on your net pay.

      Do I really have to pay the ACC levy?

      Yes. If you are earning a salary or wage in New Zealand, the ACC earners’ levy is a mandatory, legal deduction. You cannot opt out of it. It is automatically taken out of your pay by your employer alongside your PAYE tax to fund the nationwide injury cover scheme.


      Disclaimer: This is general information, not personalized financial advice. Tax laws, brackets, and IRD policies are subject to change. Always consult a registered financial adviser or an accountant for advice tailored to your specific personal circumstances.

      Date: 16/05/2026

      Author: Luca Tariciotti